Last week saw the end of September and the end of the third quarter. The S&P 500 was largely flat for the month, slipping a slight 0.45% thanks in part to weakness during the final few days. It was nevertheless a solid quarter, with the S&P 500 up 2.0% in Q3.
Fundstrat Head of Research Tom Lee acknowledged that the month’s outcome was “somewhat disappointing” to him, but in his view, the headwinds and wall of worry that confronted investors in September have turned the S&P 500 into a “coiled spring,” setting up the potential for a macro surprise in October.
Some of the catalysts for such a surprise appear to be emerging, including a dovish walkback of expectations for a rate hike at the Oct. 28 meeting of the Federal Open Market Committee. Friday’s soft jobs report was followed by even stronger expectations that officials will instead opt to pause, arguably contributing to the S&P 500 rising 0.73% today.
The broader market’s resilience during September was almost entirely due to tech leadership. On an equal-weighted basis, tech was the only sector that advanced in September. Head of Technical Strategy Mark Newton noted that, “Looking at the Russell 3000, essentially all stocks, only 20% are above their 50-day moving averages. The majority of stocks are going down.”
“The fact that the stock indices look good […] truly is testament to the strength of technology,” he added. “We have to continue to respect the fact that tech has roared back with a vengeance.”
Although the deteriorating breadth is something Newton anticipates to “stabilize,” tech “should continue to be positive.” In fact, as a sector, it could improve. On an equal-weighted basis, “we’re literally on the verge of a pretty decent breakout – for the first time since May, actually.” In other words, though giants like Meta, Microsoft, and Nvidia have been doing well, some of the smaller names could be poised to join in as well.
Chart of the Week
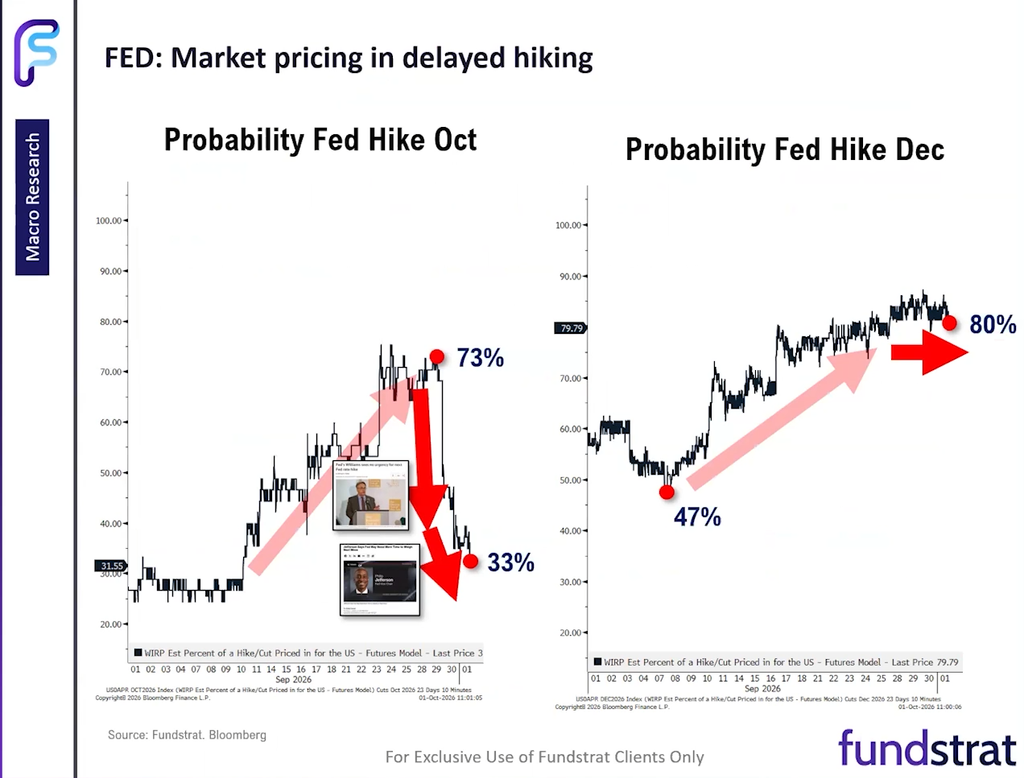
Fed funds futures trading showed that on Sept. 16, the Federal Open Market Committee’s hawkish pivot and rate hike caused anticipated odds of a second straight hike emanating from the Oct. 28 meeting to spike. In the last few days, however, a dovish walkback has materialized, with a surge of investors revising their views in favor of a likely October pause in response to dovish “Fedspeak” and a cooler-than-expected PCE report. This change in attitudes can be seen in our Chart of the Week.
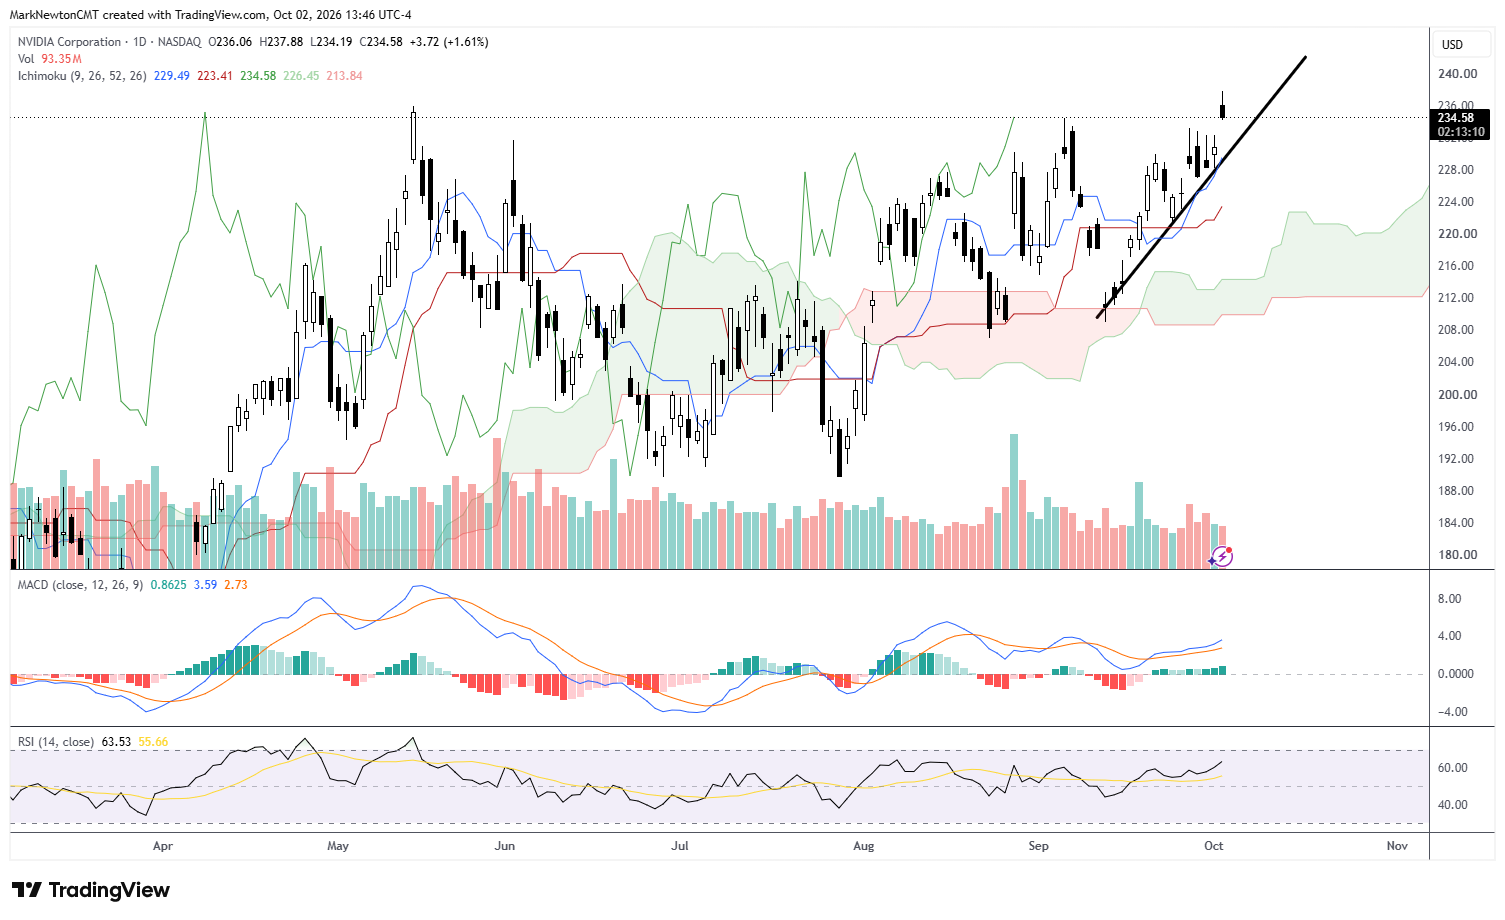
Both SPX and QQQ are holding their breakouts, but both are lower than a few hours ago as long-term rates turned back up, Crude is off earlier lows and the Dollar also turned higher. Yet, still a very constructive move for many within Technology and NVDA 1.30% in particular did make an official breakout today above 236 before pulling back ever so slightly in the last couple hours. I like using any mild consolidation from today’s breakout to buy dips and do not suspect a false/failed breakout but simply one which might require 2-3 days of “backing and filling” with max downside to near 230 before this starts to turn up more sharply in October.
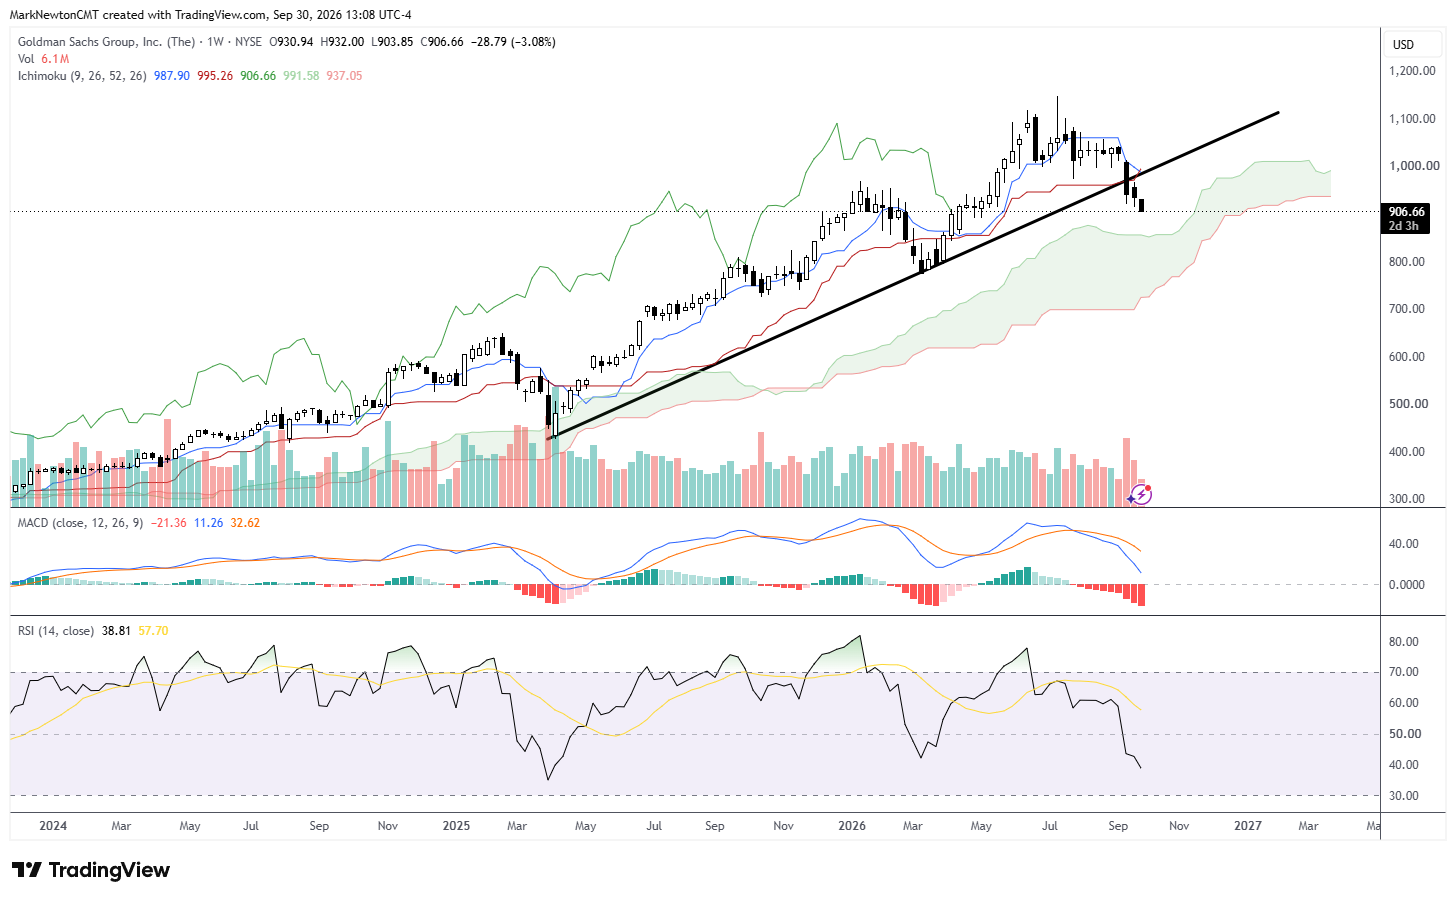
Goldman Sachs has also not been spared to the recent decline in the Financials sector. This stock is currently 22% off all-time highs and did officially break its uptrend from last Spring about two weeks ago. Following this setback, it’s important to note that GS is now right near the 38.2% Fibonacci-based area of support (Approx- $875) with Ichimoku Cloud support directly under at $857. Both of these levels could prove important, but i suspect that most of this stock’s selling pressure has already played out and it’ s closer to a material low. The key for its rally technically speaking, is for the stock to regain the downtrend which has been intact since this Summer. That requires a move above $1010 which is now the first area of resistance to monitor on a bounce. this is followed by $1050. While i like buying dips in GS, i would hold off on getting too aggressive in GS and many Financials until this can stabilize a bit more.
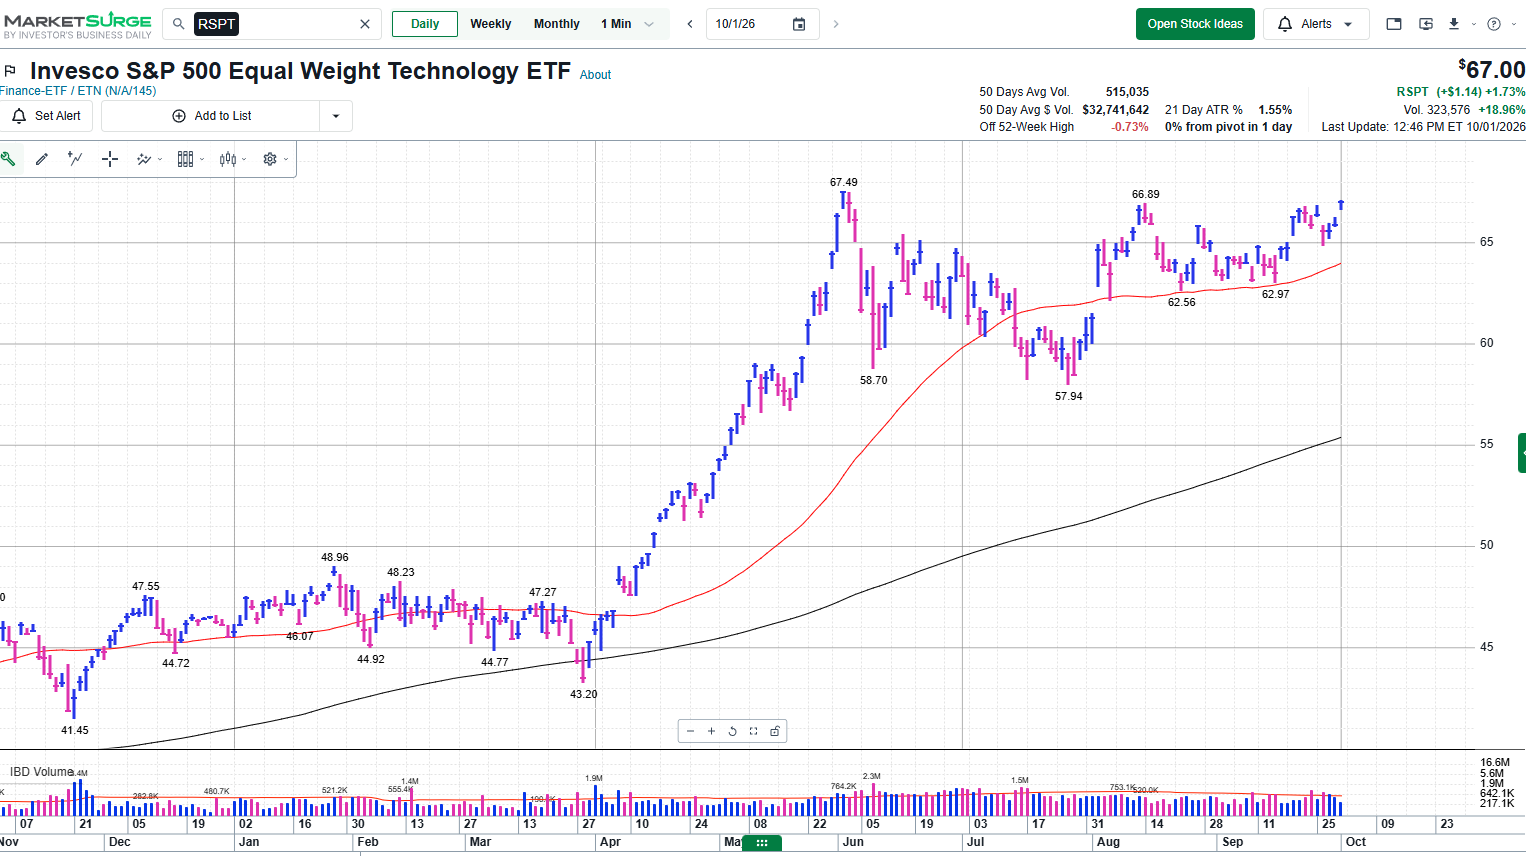
This is what the Bears are missing – Equal-wgtd Tech ( RSPT 1.04% ) on the verge of a massive 4-month breakout (which is actually happening today) with roughly 2+ hours left til the closing bell, and markets are rebounding following Fed Vice Chair Philip Jefferson saying “it may take more time before policymakers can judge whether further interest rate increases are needed to slow inflation” While market breadth is literally the worst we’ve seen since Spring, Tech is showing much better strength right now, sentiment is poor, while most Defensive sectors simply aren’t acting well at all. So, sure Fins, Discretionary being down 6%+ in a month is not great.. but Tech can and does have the power to lead & SPX, QQQ can hold up without some of these other sectors participating. This stealth correction in the broader mkt is being camouflaged.. and w/ MSFT, AAPL, NVDA, META starting to kick into gear, that’s actually MORE important as a positive for Q4 even if the next 5-6 weeks ARE choppy. Technology is outperforming and this should continue, technically for Q4.
This research is for the clients of Fundstrat Direct only. Fundstrat Direct Subscription entitles the subscriber to 1 user, research cannot be shared or redistributed. For additional information, please contact your sales representative or Fundstrat Direct at fundstratdirect.com.
Conflicts of Interest
This research contains the views, opinions and recommendations of Fundstrat Direct. At the time of publication of this report, Fundstrat Direct does not know of, or have reason to know of any material conflicts of interest.
General Disclosures
Fundstrat Direct is an independent research company and is not a registered investment advisor and is not acting as a broker dealer under any federal or state securities laws.
Fundstrat Direct is a member of IRC Securities’ Research Prime Services Platform. IRC Securities is a FINRA registered broker-dealer that is focused on supporting the independent research industry. Certain personnel of Fundstrat Direct (i.e. Research Analysts) are registered representatives of IRC Securities, a FINRA member firm registered as a broker-dealer with the Securities and Exchange Commission and certain state securities regulators. As registered representatives and independent contractors of IRC Securities, such personnel may receive commissions paid to or shared with IRC Securities for transactions placed by Fundstrat Direct clients directly with IRC Securities or with securities firms that may share commissions with IRC Securities in accordance with applicable SEC and FINRA requirements. IRC Securities does not distribute the research of Fundstrat Direct, which is available to select institutional clients that have engaged Fundstrat Direct.
As registered representatives of IRC Securities our analysts must follow IRC Securities’ Written Supervisory Procedures. Notable compliance policies include (1) prohibition of insider trading or the facilitation thereof, (2) maintaining client confidentiality, (3) archival of electronic communications, and (4) appropriate use of electronic communications, amongst other compliance related policies.
Fundstrat Direct does not have the same conflicts that traditional sell-side research organizations have because Fundstrat Direct (1) does not conduct any investment banking activities, and (2) does not manage any investment funds.
This communication is issued by Fundstrat Direct and/or affiliates of Fundstrat Direct. This is not a personal recommendation, nor an offer to buy or sell nor a solicitation to buy or sell any securities, investment products or other financial instruments or services. This material is distributed for general informational and educational purposes only and is not intended to constitute legal, tax, accounting or investment advice.
The statements in this document shall not be considered as an objective or independent explanation of the matters. Please note that this document (a) has not been prepared in accordance with legal requirements designed to promote the independence of investment research, and (b) is not subject to any prohibition on dealing ahead of the dissemination or publication of investment research.
Intended for recipient only and not for further distribution without the consent of Fundstrat Direct.
This research is for the clients of Fundstrat Direct only. Additional information is available upon request. Information has been obtained from sources believed to be reliable, but Fundstrat Direct does not warrant its completeness or accuracy except with respect to any disclosures relative to Fundstrat Direct and the analyst’s involvement (if any) with any of the subject companies of the research. All pricing is as of the market close for the securities discussed, unless otherwise stated. Opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice. Past performance is not indicative of future results. This material is not intended as an offer or solicitation for the purchase or sale of any financial instrument. The opinions and recommendations herein do not take into account individual client circumstances, risk tolerance, objectives, or needs and are not intended as recommendations of particular securities, financial instruments or strategies. The recipient of this report must make its own independent decision regarding any securities or financial instruments mentioned herein. Except in circumstances where Fundstrat Direct expressly agrees otherwise in writing, Fundstrat Direct is not acting as a municipal advisor and the opinions or views contained herein are not intended to be, and do not constitute, advice, including within the meaning of Section 15B of the Securities Exchange Act of 1934. All research reports are disseminated and available to all clients simultaneously through electronic publication to our internal client website, fundstratdirect.com. Not all research content is redistributed to our clients or made available to third-party aggregators or the media. Please contact your sales representative if you would like to receive any of our research publications.