
Trends for Equities remain upward sloping based on Equal-weighted SPX, though they are still quite choppy in the short run when eyeing both SPX and QQQ. While the Advance/Decline line recently pushed back to new highs for NYSE securities, it’s still troubling that recent lackluster volume and short-squeeze activity has been ongoing as major US indices churn near all-time high territory. The recent Software and “Mag 7” weakness has resulted in Technology falling out of favor and has actually resulted in SPX breaking down from multi-year uptrends vs the All-Country World index. Furthermore, the push into Defensive securities continues as the strength in Consumer Staples has begun to spread more rapidly to Telecom and Utilities in the last week. While it’s difficult to consider that trends are changing barring an actual breakdown in intermediate-term price trends and breadth gauges (which hasn’t happened) there are a plethora of advance warning signs that are starting to crop up which are important to pay attention to at this stage of the rally. Overall, I am expecting a choppy push higher up to the 7100-7200 area, but feel like upside should be limited to around 3% higher. Meanwhile, any drop under early February lows at 6780.13 would serve to turn trends negative, and this remains the “line in the sand” for trend followers.
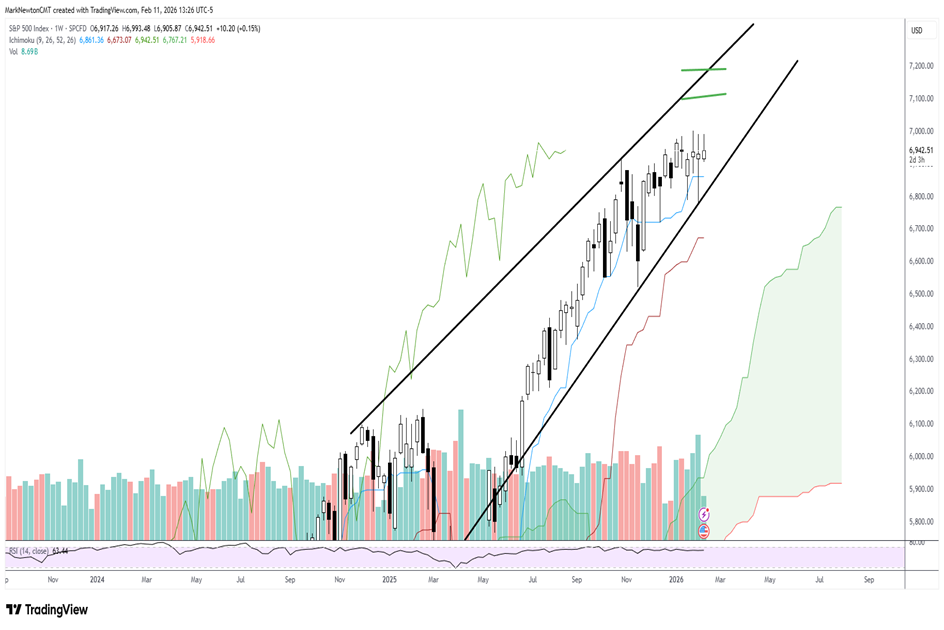
The weekly SPX chart below is the proper way to view this uptrend channel of recent years, and the area right near 7150 looks quite important as resistance on further gains in the weeks ahead.
Meanwhile, support lies near 6780 and cannot be broken without violating this uptrend as ^SPX pulls back to new monthly lows.
While the wild dispersion across Equities hasn’t served to derail this trend just yet, it’s been successful in resulting in a recent cluster of “Hindenburg Omen” signals, which often can serve as a possible warning for a coming change in trend.
The ongoing bifurcation in Technology remains troubling as Software continues to have difficulty stabilizing, while Semiconductor and Data Storage stocks reach higher levels of overbought territory.
As can be seen below, the path of least resistance remains to the upside, and I do believe a bullish stance still makes sense as ^SPX and QQQ attempt to push back to new all-time highs. However, in the weeks ahead, keeping a close eye on “key” support (SPX-6780) makes a lot of sense in the event that prices begin to turn lower.
S&P 500 Index
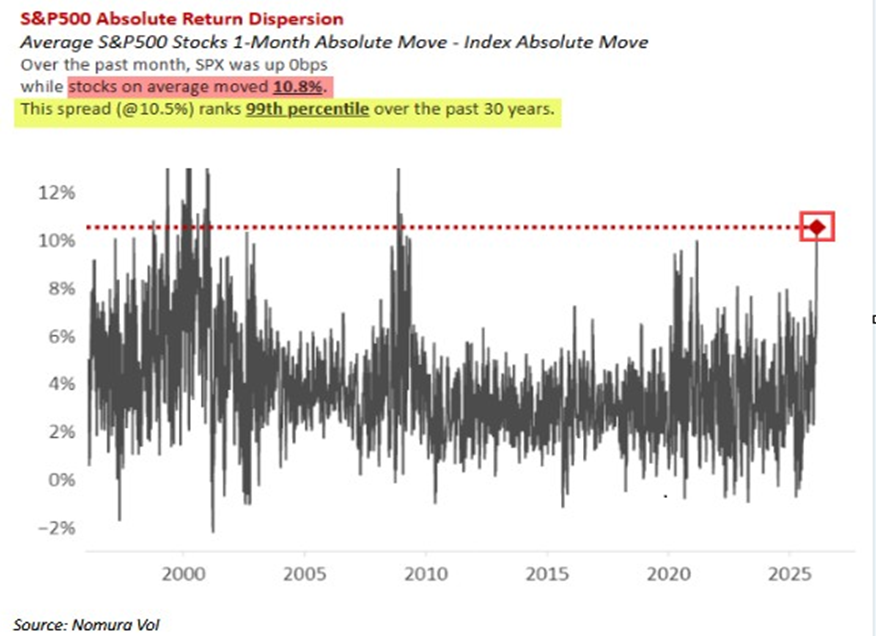
Dispersion has reached very high levels compared to the underlying index, which is something to keep a close eye on
Many investors might feel that markets “feel” a lot more negative than what the ^SPX and QQQ have shown from a price perspective lately, which largely has proven sideways in recent months.
While the Equal-weighted ^SPX, DJ Transportation Average, DJIA, and Russell 2000 index have all pushed back to new all-time high territory, ^SPX and QQQ certainly have diverged negatively.
Furthermore, the “Absolute Return Dispersion” has now reached the 99th percentile of the past 30 years. In other words, the spread between the S&P 500 stocks’ 1-month Absolute move, subtracting the absolute move in the ^SPX, has risen to very high levels.
Thus, S&P 500 individual securities feel quite volatile, though the index has not made much progress in either direction in the last month. Overall, this won’t be a problem for ^SPX and QQQ until trends are broken, but it’s worth understanding that the US stock market is far more volatile these days than the index has shown in recent weeks.
S&P 500 Absolute Return Dispersion
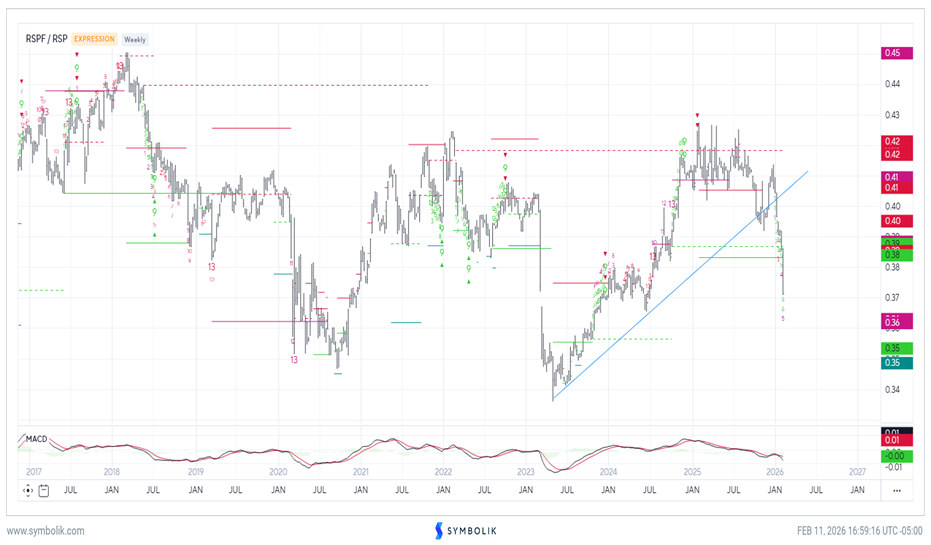
Financials have begun to drop much more sharply in recent weeks
Many investors might know that Financials has proven to be the worst-performing sector of all major sectors Year-to-Date (YTD).
This is ironic given that Financials are the third largest sector within SPX by market capitalization, and ^SPX lies just 35 points from a new all-time high close.
I discussed the Banks (KBWB) outperformance over the Broker Dealers (IAI) last week, and this has continued, while the Equal-weighted Financials sector ETF by Invesco (RSPF) has plummeted to the lowest levels since 2024 vs. the Equal-weighted SPX ETF (RSP).
Given the abnormally large high-to-low range of the last couple of weeks, it’s difficult to make a strong case for an imminent bottom in Financials.
Thus, it’s going to be important to give this sector some close attention in the weeks ahead as Defensive sectors continue to outperform and make headway higher.
RSPF/RSP
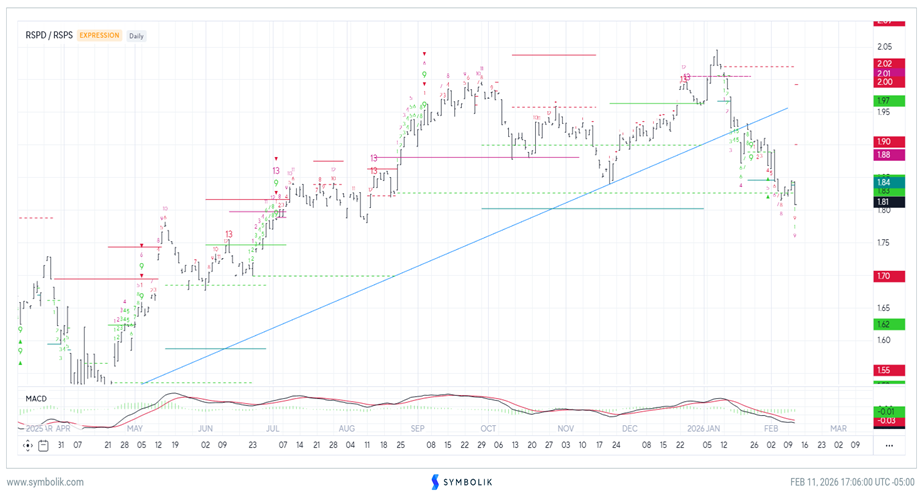
Consumer Discretionary has fallen to the lowest relative level vs. Consumer Staples since last Summer
The Consumer Discretionary Equal-weighted ETF (RSPD) has now fallen on a relative basis vs. the Equal-weighted Consumer Staples ETF (RSPS) to the lowest levels since last Summer.
This was a ratio I had discussed a few weeks ago, but the technical damage has continued to worsen as “Staples” is making much better progress than “Discretionary” (despite the Strength in Building and Construction names).
This extreme kind of rotation is often thought to be a harbinger of a “risk-off” period for stocks when it grows severe, but as discussed, Utilities and Telecom are now beginning to show more and more strength and joining Staples in their outperformance this week.
Overall, this Defensive trading needs to be monitored, but at present, further Staples outperformance looks likely over Discretionary in the weeks ahead.
RSPD/RSPS