


Treasury Continues Moving Toward More Activist Duration Management
Treasury continues moving in the direction of more activist duration management. Last week, Treasury increased the size of its long-duration buyback operations from roughly $2B to at least $4B per operation. Mechanically, that increase is relatively modest, but I thought the signal was much more important. Treasury is increasingly demonstrating a willingness to intervene as pressure builds in the long end.
Today, Treasury Secretary Scott Bessent went a step further, suggesting that Treasury could potentially draw down the roughly $950B TGA balance to finance additional purchases of longer-term Treasuries.
Whether that ultimately happens remains to be seen, but the implications would be meaningful. A TGA-funded buyback would not simply remove duration from the market. Drawing down the TGA would simultaneously transfer cash into the private sector and increase bank reserves, making the policy directly liquidity-positive in our framework.
The TGA would eventually need to be rebuilt, likely through additional bill issuance, but in aggregate this would accelerate the “Treasury Operation Twist” dynamic we discussed last week. Treasury removes duration from the market, replaces it with shorter-term liabilities, and potentially creates conditions that ultimately require greater reserve-management purchases from the Fed.
In my view, that is increasingly consistent with what I have characterized as YCC-lite or financial repression-lite, and it would represent a decidedly more constructive liquidity regime for crypto.
Strategy Creates a New $1.6B Discretionary Cash Pool
Strategy’s latest 8-K reveals that the company sold ~$2B of common stock last week, none of which went toward buying BTC. Of those proceeds, $136M funded a 5th consecutive week of STRC repurchases and only ~$300M went to the USD Reserve. The remaining ~$1.6B went toward a newly created cash pool titled “USD Cash,” which can seemingly be deployed across virtually any capital markets activity, including acquiring BTC, servicing preferred dividends and debt, repurchasing MSTR or preferred stock, retiring converts, or increasing the USD Reserve.
I think this mostly reflects Strategy’s unwillingness to finance ordinary BTC accumulation with anything other than STRC proceeds for the time being. However, it also further reinforces the company’s shift from programmatic accumulation toward the more active, conditional approach outlined on the Q2 call. Notably, Strategy has now gone two consecutive weeks with zero BTC activity, with holdings unchanged, even as BTC rallied toward ~$78K. That is a meaningful departure from the historical playbook.
From a markets perspective, USD Cash creates something resembling a “plunge protection” bid. Despite management’s preference to fund ordinary BTC accumulation through STRC, USD Cash is explicitly designed to allow Strategy to “respond more quickly to market conditions, including dislocations in the markets for bitcoin or Strategy’s securities.” Thus, I would expect at least some of this capital to be deployed into a sizeable drawdown. The important caveat is that the destination of that bid depends on where the more pronounced dislocation occurs. In a June-style episode where STRC breaks into the low-$70s, defending the credit would almost certainly take priority over adding BTC. The BTC backstop is therefore really a residual claim on USD Cash after the preferred stack is defended.
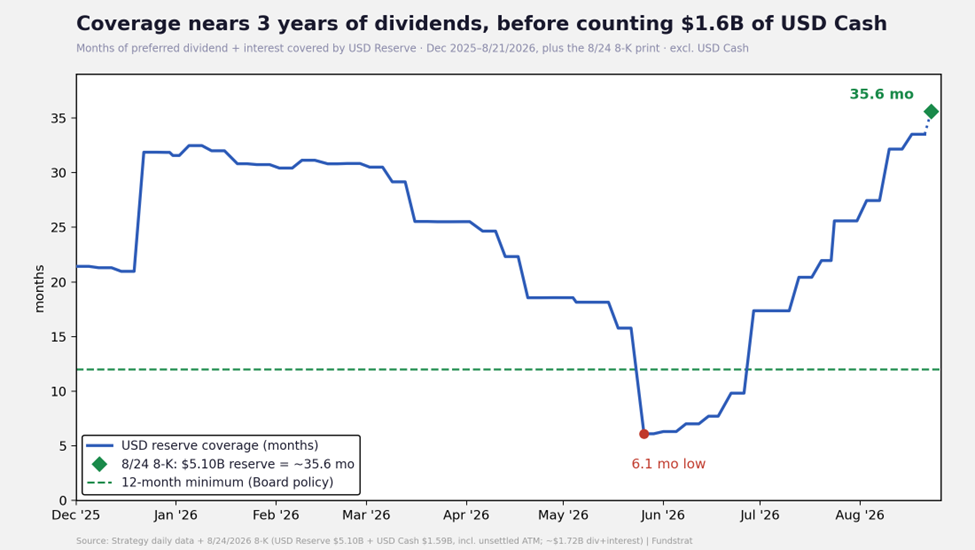
Also, worth noting that MSTR’s USD Reserve is now up to nearly 3 years of coverage.
Post-Squeeze Follow-Through Continues to Look Healthy
Finally, I think the market action following last week’s short squeeze continues to improve the case that we may be seeing something more durable than a tactical bounce. The initial move was unquestionably amplified by short liquidations. What matters is what happened afterward.
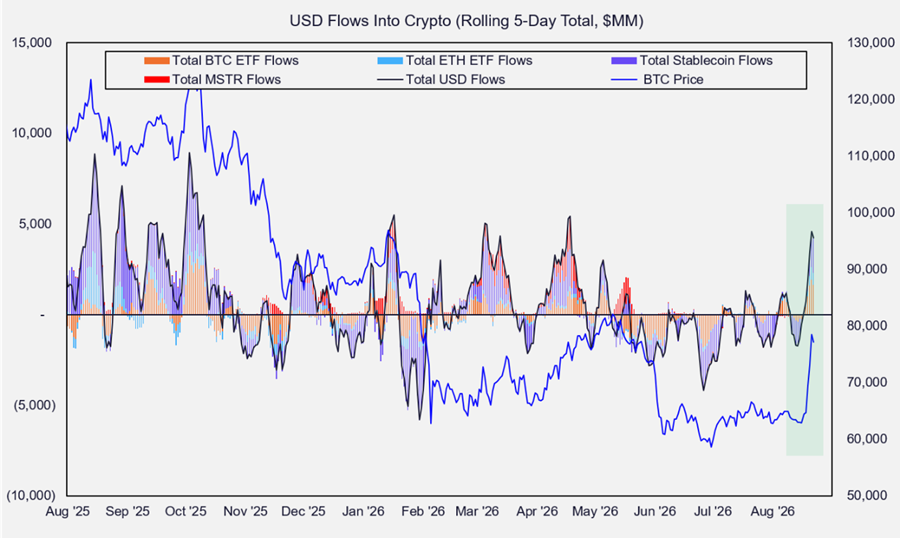
We have now seen meaningful follow-through in the spot market, including strong BTC and ETH ETF inflows, higher trading volumes, and substantial stablecoin issuance. Rolling five-day ETF inflows across BTC and ETH have reached their strongest levels of the year.
The options market is also showing an important change. During prior tactical rallies this year, investors were willing to chase short-dated upside but remained reluctant to pay for calls further out the curve. This time, 25-delta skew has shifted constructively across one-month, three-month, and even longer-dated tenors.
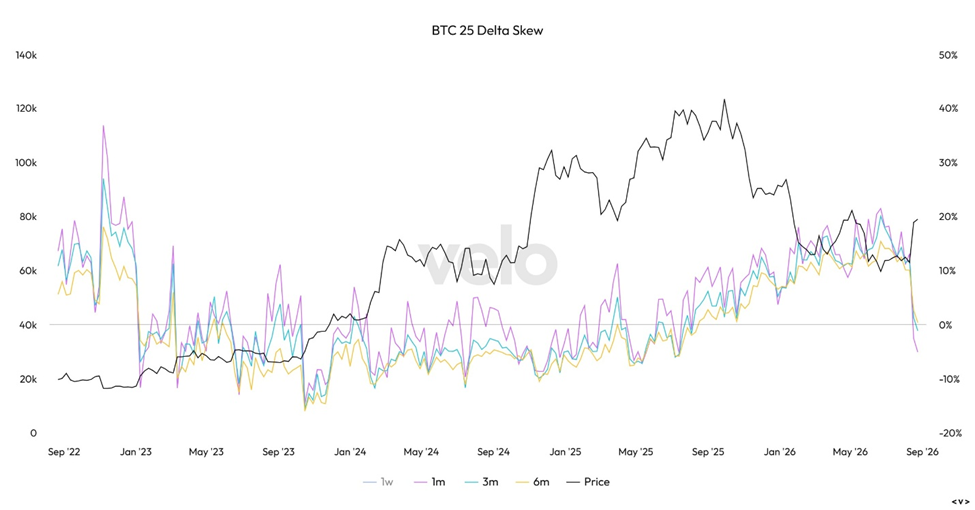
To me, that is more significant than short-dated call chasing. It suggests investors are increasingly willing to pay for durable upside exposure, rather than simply betting on a temporary squeeze.
Perhaps most importantly, this occurred with zero incremental BTC demand from Strategy. If Strategy eventually begins deploying STRC proceeds or USD Cash into BTC while ETF flows and broader spot demand remain healthy, that would add another potentially meaningful leg to the demand side of the equation.
Bottom Line
The evidence for a broader regime change continues to build. Treasury is increasingly signaling that it is willing to actively manage duration and potentially deploy TGA liquidity to resist pressure in the long end, which could simultaneously suppress real yields and accelerate liquidity growth. Strategy, meanwhile, has rebuilt its balance sheet and created a sizeable discretionary cash pool that gives it the ability to respond countercyclically to future dislocations. Most importantly, last week’s short squeeze has been followed by genuine spot demand, improving longer-dated options positioning, and strong ETF flows, even without Strategy participating as a BTC buyer.
Taken together, I think these developments further reinforce the more constructive view I plan to lay out in tomorrow’s webinar. The bottoming process increasingly looks complete, the macro regime is beginning to turn more favorable, and the appropriate posture is shifting from selling strength toward adding on meaningful pullbacks.
Tickers in this video: BTC 1.17% ETH 1.73% STRC MSTR
______________________________
PS: If you are enjoying our service and its evidence-based approach, please leave us a positive 5-star review on Google reviews —> Click here.