


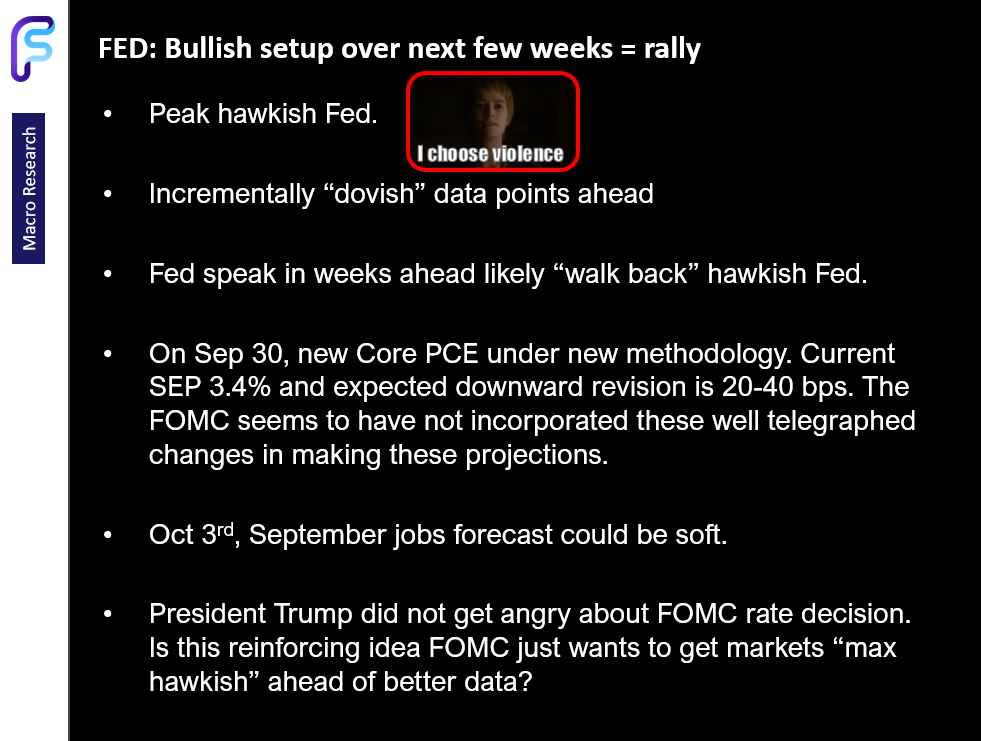
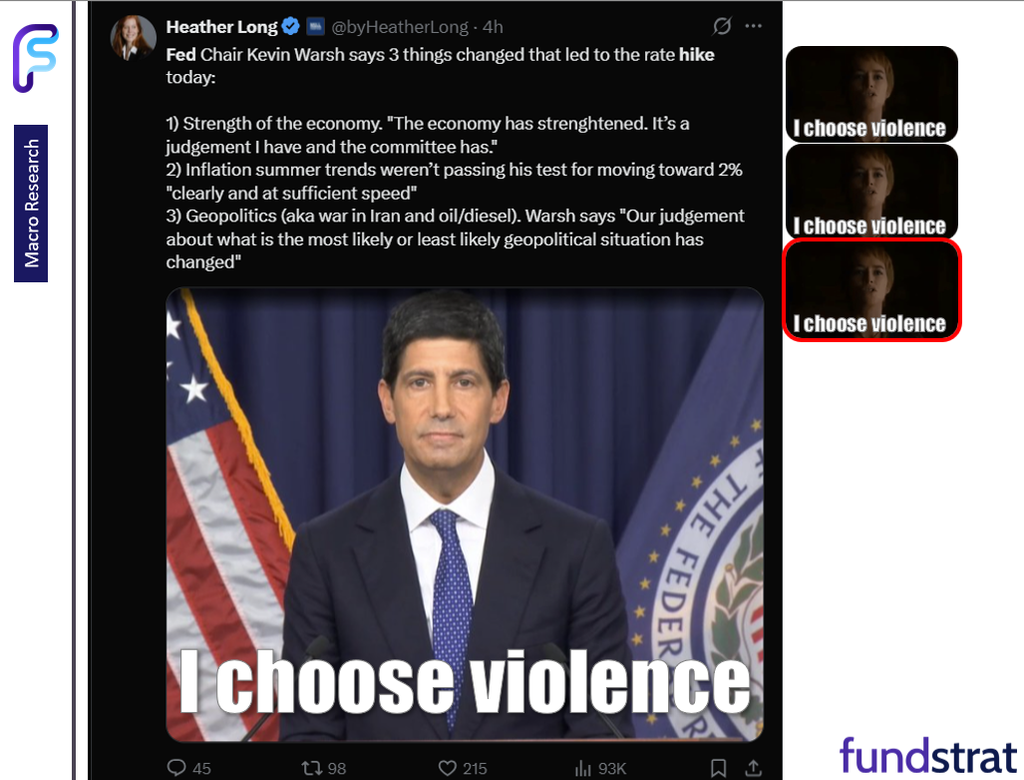
This past Wednesday, Fed Chair Warsh chose “violence” taking a maximum hawkish stance on inflation and stocks sold off sharply closing down -1%. Thursday, equity markets rallied erasing those losses and now up ~1% from Tuesday’s close. To us, this makes sense. As we discussed in our Wednesday commentary, the “max hawkish” stance by Fed Chair Warsh arguably is actually a bullish setup for equities:
- We see multiple reasons the Fed decision has created a bullish setup:
1. Peak hawkish Fed = hard to see “more hawkish”
2. We see incrementally “dovish” data points ahead = less bad
3. Fed speak in weeks ahead likely “walk back” hawkish Fed
4. On Sep 30, new Core PCE under new methodology. Current SEP 3.4% and expected downward revision is 20-40 bps. The FOMC seems to have not incorporated these well telegraphed changes in making these projections.
5. Oct 3rd, September jobs forecast could be soft
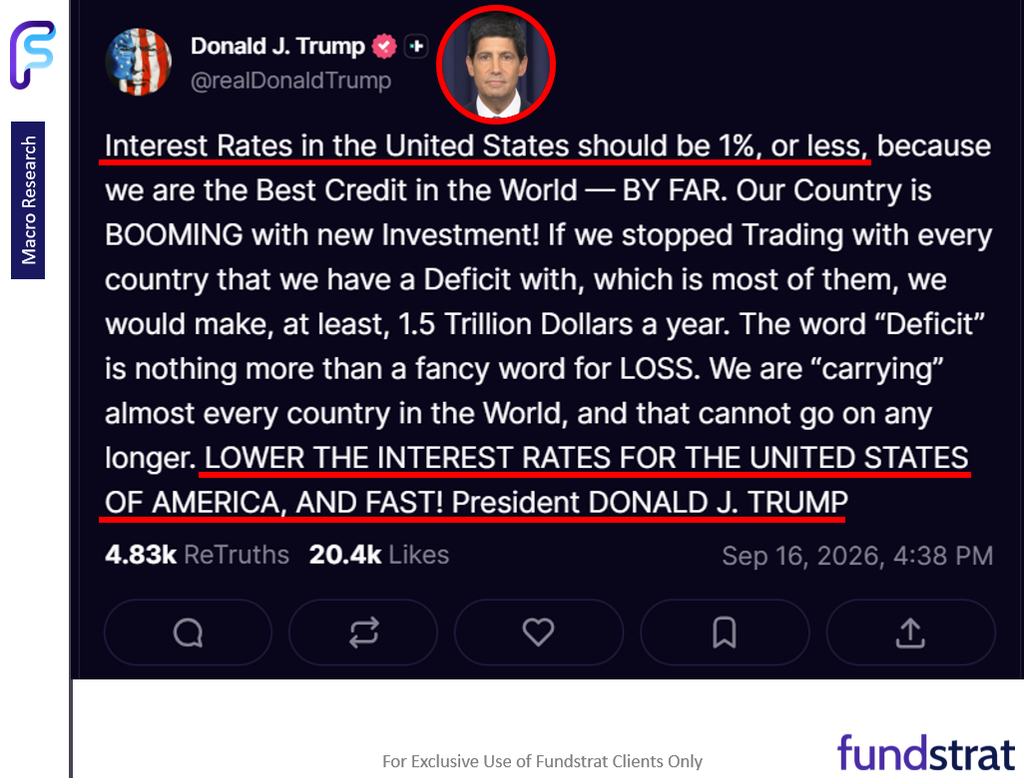
6. President Trump did not get angry about FOMC rate decision. Is this reinforcing idea FOMC just wants to get markets “max hawkish” ahead of better data? - Thursday saw encouraging price improvements (albeit small) in yields, oil and VIX.
– US 10-yr down to 4.93%, below Wed’s low of 4.95% and well off of 5.04% seen Tuesday.
– US WTI is down to $101 below $106 a few days ago, although the path of war remains unclear
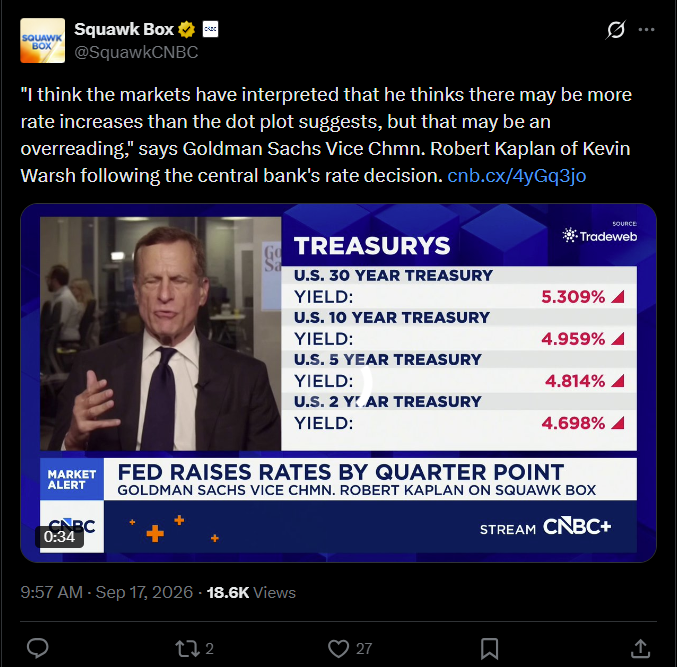
– VIX closed at 15 and well off 18 seen Wednesday. - Investors bought the dip and arguably for the right reason. As we noted, there are 6 reasons the FOMC decision and maximum hawkish stance is actually a bullish setup. In fact, even former Fed officials note this. On Thu am, former Dallas Fed President, Robert Kaplan, noted:
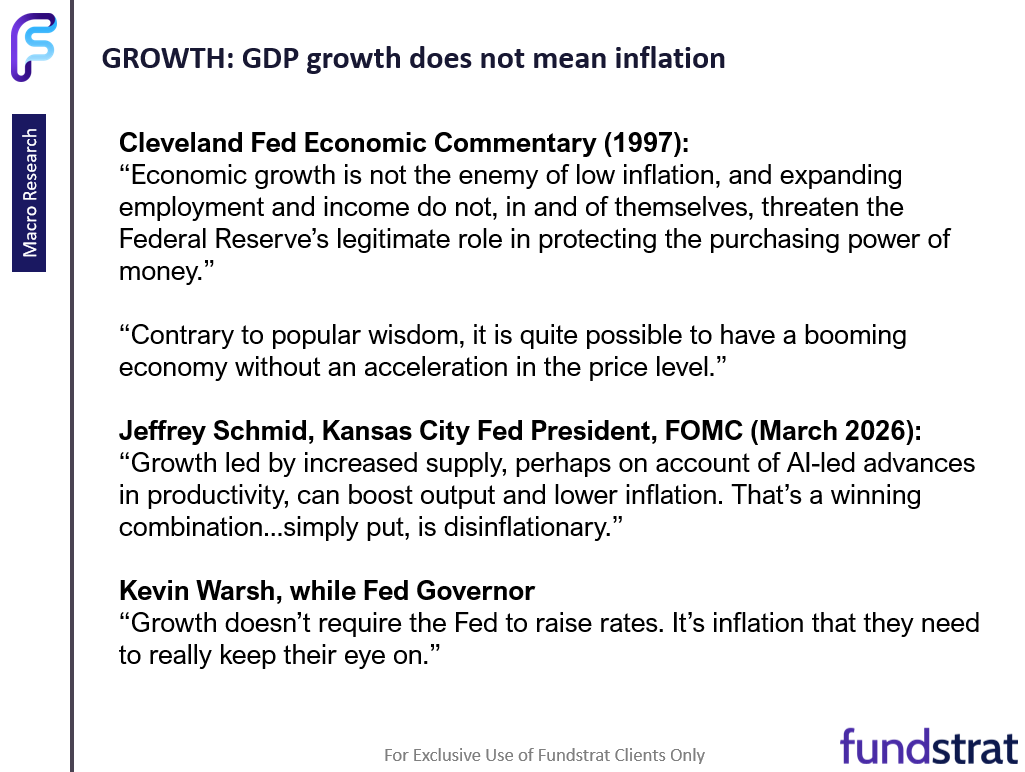
– “I think the markets have interpreted that [Warsh] thinks there may be more rate increases than the dot plot suggests, but that may be an overreading,” - To us, equity and bond investors are arguably over-reacting. While nobody wants inflation, it seems like the investors and policymakers have simply lost patience and do want to leave it to chance to see inflation rates fall. But, we have similarly noted that not only is core PCE set to fall in coming months (per Goldman analysis) but equally important, there are methodological reasons for why core PCE is 3.4% versus core CPI at 2.35%. And if they are set to converge towards CPI in coming months, tightening today is a mistake.
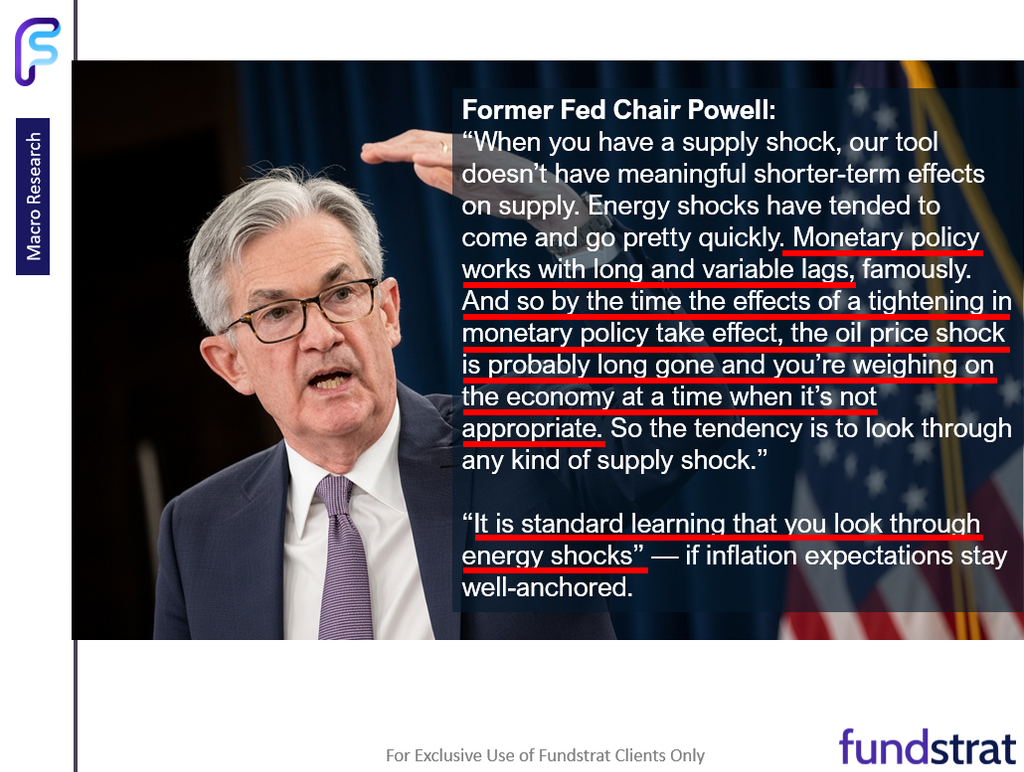
- The Fed has stated that monetary policy has long and variable lags. Thus, the change in the Fed funds rate today will take 6 months to see the impacts on inflation. 6 months from now is March 2027.
- So here is the key exercise, and let’s time stamp it:
– if core PCE YoY falls 100bp between now and March 2027
– these declines are not a result of the Fed hikes made in Sept
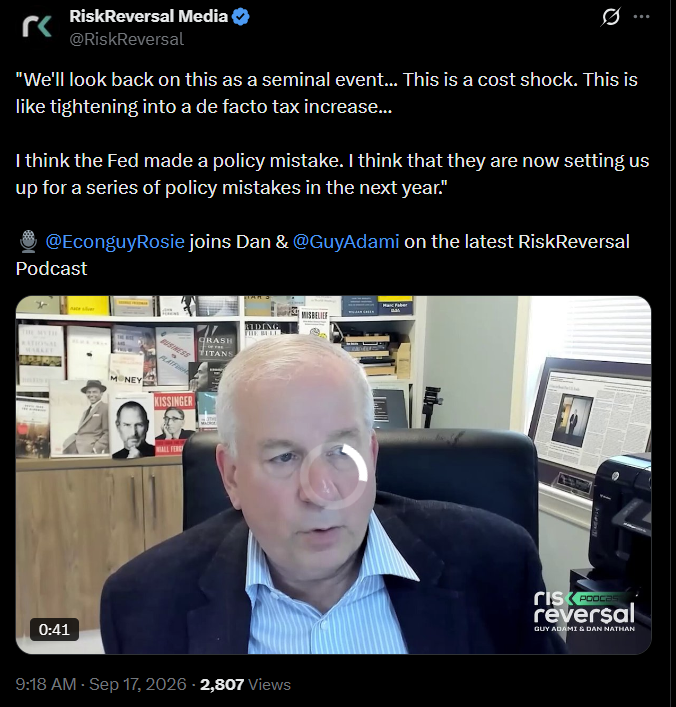
– thus, the hike Wednesday is a policy error. - As David Rosenberg, former Merrill Chief Economist, notes:
– “We’ll look back on this as a seminal event… This is a cost shock.”
– “This is like tightening into a de facto tax increase…”
– “I think the Fed made a policy mistake.”
– “I think that they are now setting us up for a series of policy mistakes in the next year.” - If Core PCE starts with a “2” in early 2027, this will show that all the “inflationistas” economists and pundits were just impatient. So, this is worth watching.
- In the coming week, there will be a lot of Fed speak, and this, in our view, will result in FOMC walking back on the “max hawkish” words of Warsh:
– 9/21 Mon 6:30 AM ET: Goolsbee Speaks About Monetary Policy
– 9/22 Tue 10:05 AM ET: Williams Gives Keynote Remarks (voting)
– 9/22 Tue 1:00 PM ET: Barkin Speaks to the CFA Society Baltimore
– 9/24 Thu 4:10 AM ET: Williams Speaks During Moderated Discussion (voting)
– 9/24 Thu 8:00 AM ET: Barkin In Fireside Chat With Economic Club of Washington
– 9/24 Thu 8:50 AM ET: Hammack Delivers Opening Remarks at Inflation Conf. (voting)
– 9/24 Thu 10:10 AM ET: Paulson Speaks At Fintech Conference (voting)
– 9/25 Fri 5:15 AM ET: Williams Participates in Policy Panel (voting)
– 9/25 Fri 2:00 PM ET: Hammack Participates In Policy Panel Discussion (voting) - This week we had a pivotal FOMC Decision and Press Conference on Wednesday:
– 9/15 Tue 8:30 AM ET: Sep Empire Manufacturing Survey 7.6 vs 15.0e
– 9/16 Wed 8:30 AM ET: Aug Retail Sales 1.2% vs 0.8%e
– 9/16 Wed 10:00 AM ET: Sep NAHB Housing Market Index 32 vs 34e
– 9/16 Wed 2:00 PM ET: Sep FOMC Decision +25bp, 3.75%
– 9/16 Wed 4:00 PM ET: Jul Net TIC Flows $84b
– 9/17 Thu 8:30 AM ET: Sep Philly Fed Business Outlook 37.8 vs 32.1e - Next week we have Regional Fed survey releases throughout the week, as well as preliminary PMI data on Wednesday:
– 9/21 Mon 8:30 AM ET: Aug Chicago Fed Nat Activity Index -0.06e
– 9/22 Tue 10:00 AM ET: Sep Richmond Fed Manufacturing Survey
– 9/23 Wed: September Macro Update and Top Stock Ideas Webinar
– 9/23 Wed 9:45 AM ET: Sep P S&P Global Manufacturing PMI
– 9/23 Wed 9:45 AM ET: Sep P S&P Global Services PMI
– 9/24 Thu 10:00 AM ET: Aug New Home Sales 615ke
– 9/24 Thu 11:00 AM ET: Sep Kansas City Fed Manufacturing Survey
– 9/25 Fri 8:30 AM ET: Aug P Durable Goods Orders MoM -0.3%e
– 9/25 Fri 10:00 AM ET: Sep F U. Mich. 1yr Inf Exp
Bottom line: We expect stocks to rally into month-end
The S&P 500 is down -0.5% so far this month. We think there is a positive setup into month-end and the up move could be very sharply positive — aka “face ripper”
- Foremost, we believe underlying fundamentals remain solid
- Investor sentiment remains cautious and this adds asymmetry to risk/reward
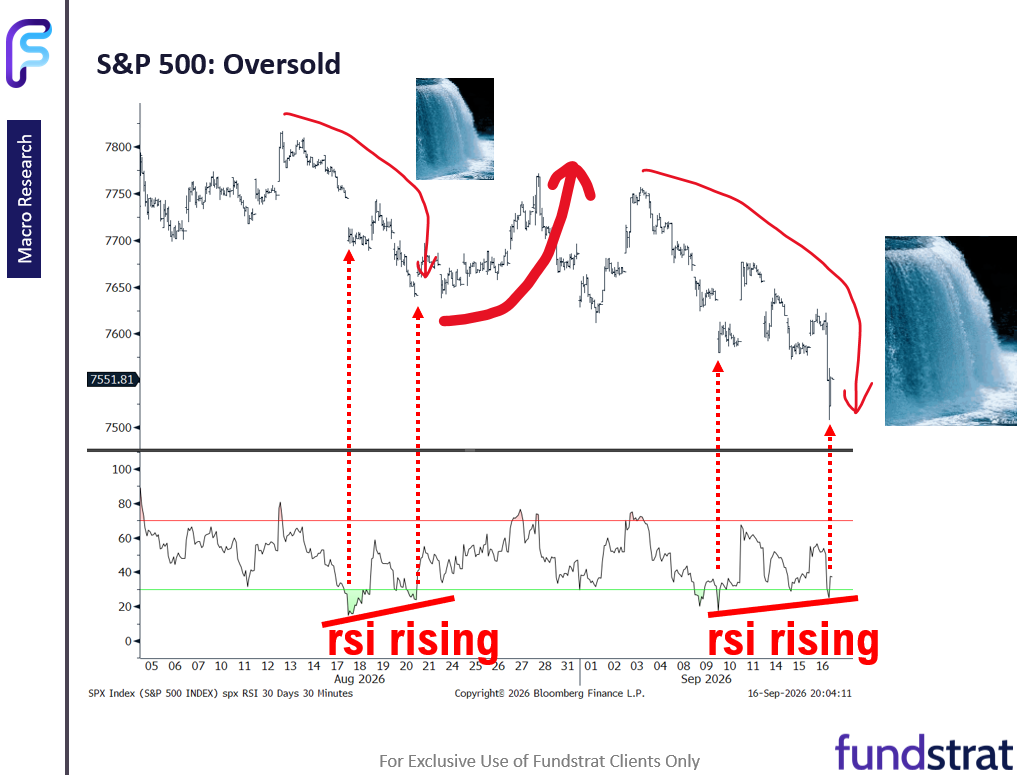
- Equities saw a waterfall decline in the past week. In mid-August, such a waterfall decline was followed by a rally
- Incremental data, in our view, will be dovish, which will fuel further upside
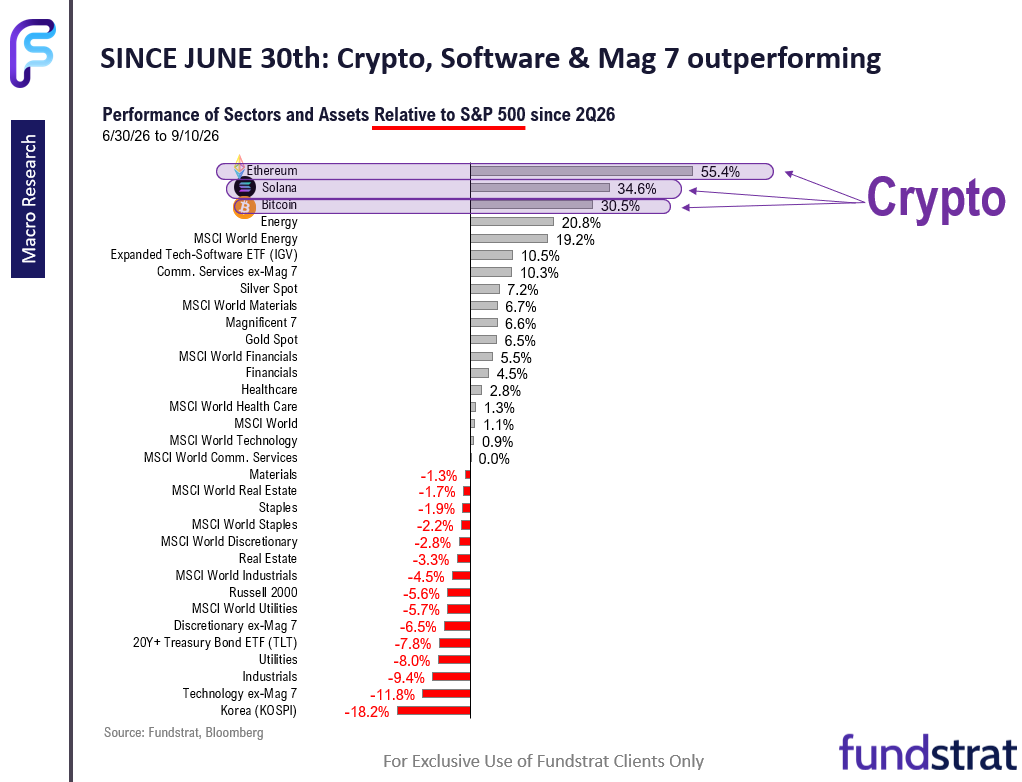
The strength in crypto remains notable. Ethereum ETH 5.89% remains the best performing major macro asset in 3Q26 so far. This bodes well for crypto to outperform not only into month-end but also 4Q26.
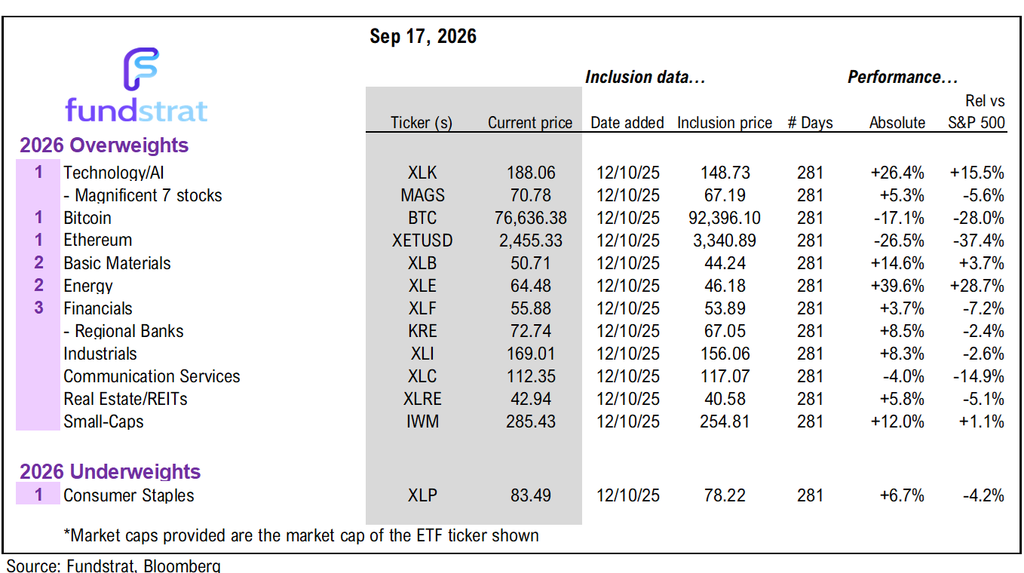
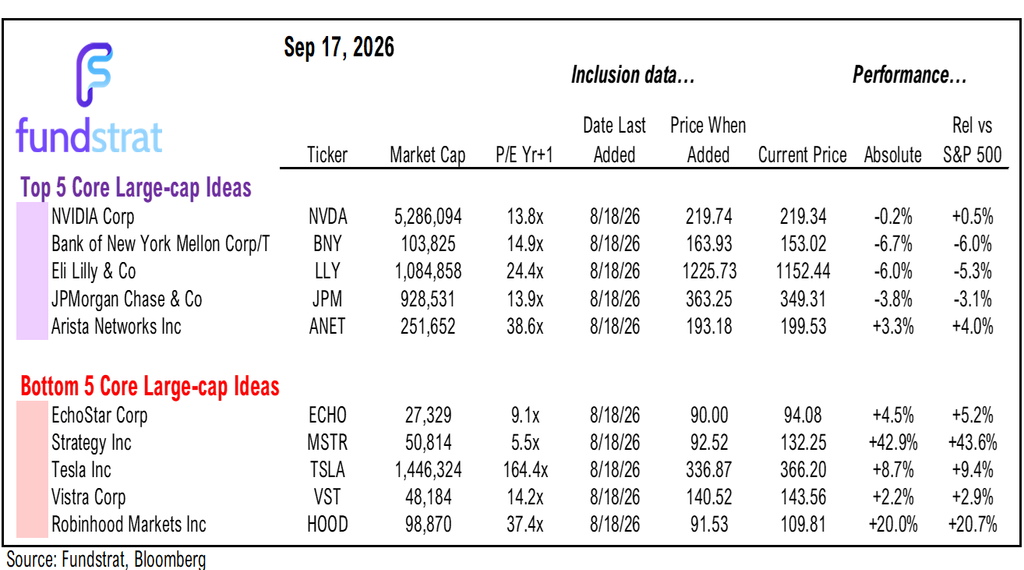
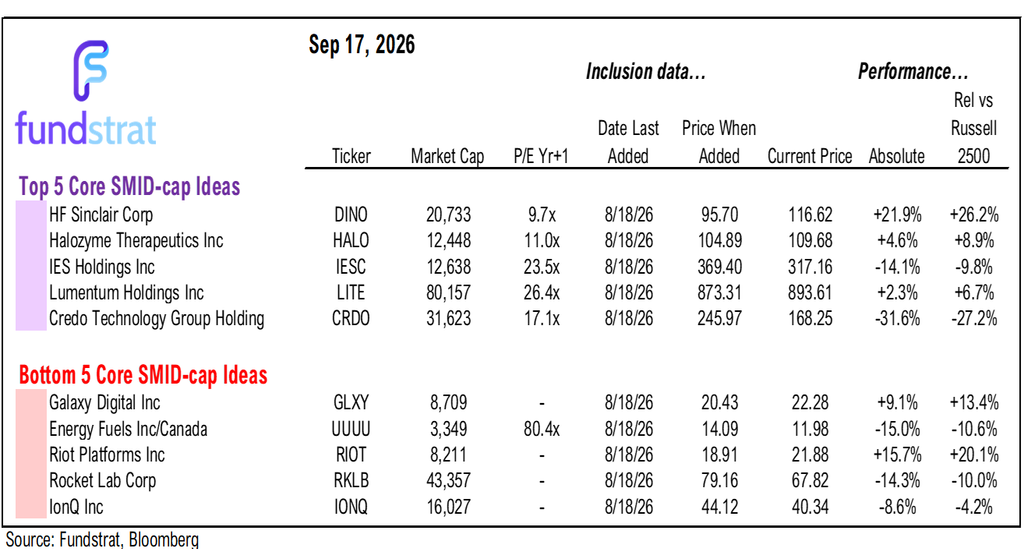
Part I: 46 Large-cap Core Ideas: Updated list is below
Large-Cap Core Stock Ideas are large-cap stocks that appear in multiple of our investment strategies.
- Consider these stocks our top stock picks and thus, the higher quality ideas.
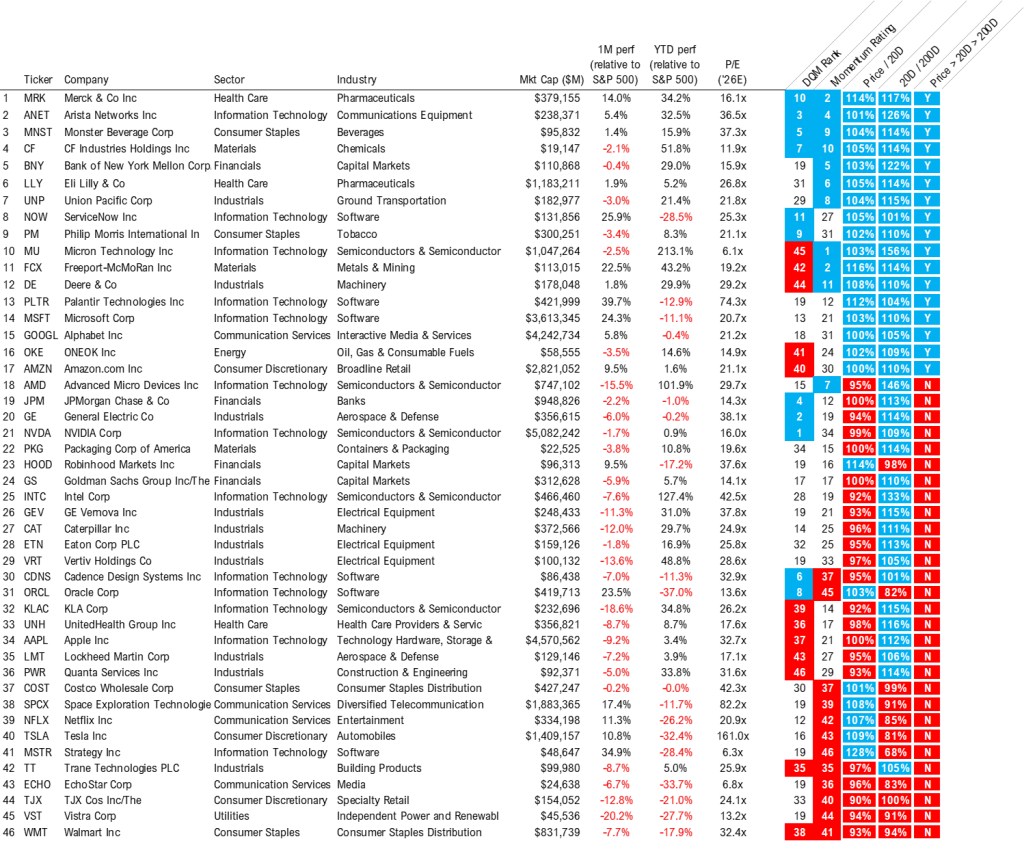
The Current Large-cap Core List as of 8/21/2026 is as follows:
Communication Services: ECHO, GOOGL, NFLX
Consumer Discretionary: AMZN, TJX, TSLA
Consumer Staples: COST, MNST, PM, WMT
Energy: OKE
Financials: BNY, GS, HOOD, JPM
Health Care: LLY, MRK, UNH
Industrials: CAT, DE, ETN, GE, GEV, LMT, PWR, SPCX, TT, UNP, VRT
Information Technology: AAPL, AMD, ANET, CDNS, INTC, KLAC, MSFT, MSTR, MU, NOW, NVDA, ORCL, PLTR
Materials: CF, FCX, PKG
Utilities: VST
Part II: 65 SMID Core Ideas: Updated list is below
SMID Core Ideas are small and mid-cap stocks that appear in multiple of our investment strategies.
- We believe SMID Core List could benefit from the multiple themes and secular tailwinds.
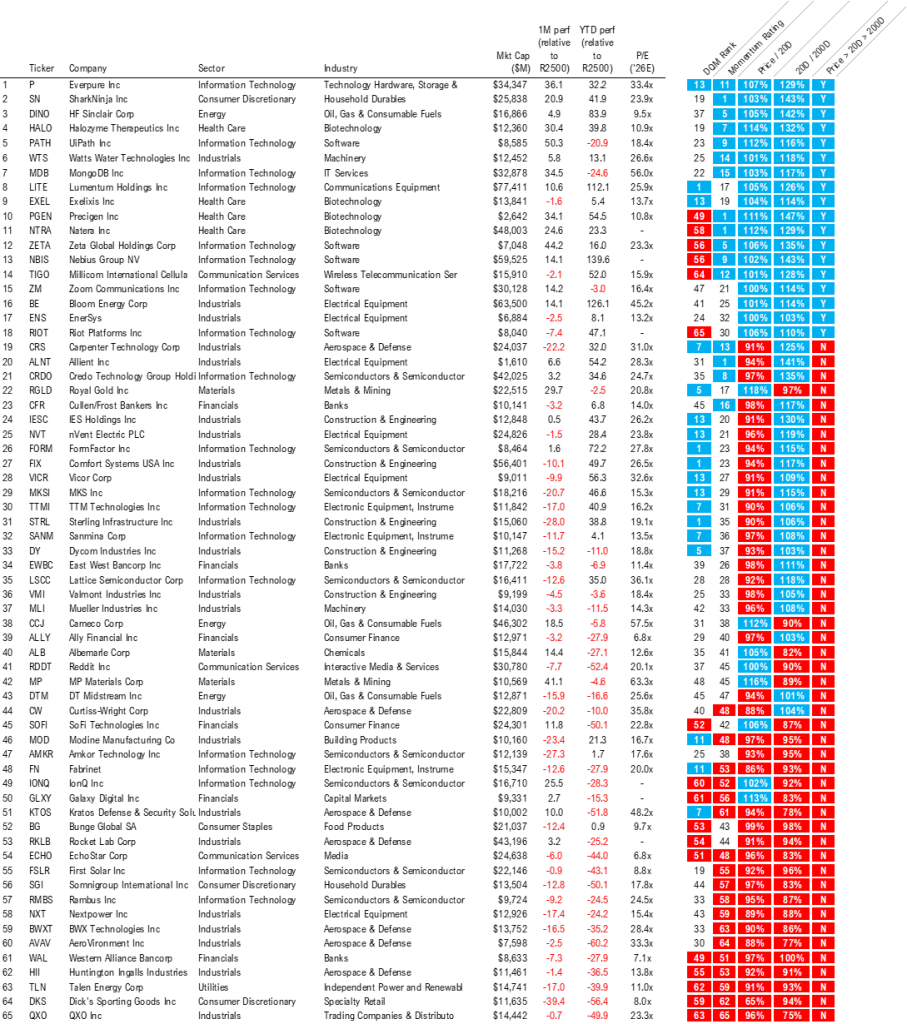
The Current SMID Core List as of 8/21/2026 is as follows:
Communication Services: ECHO, RDDT, TIGO
Consumer Discretionary: DKS, SGI, SN
Consumer Staples: BG
Energy: CCJ, DINO, DTM
Financials: ALLY, CFR, EWBC, GLXY, SOFI, WAL
Health Care: EXEL, HALO, NTRA, PGEN
Industrials: ALNT, AVAV, BE, BWXT, CRS, CW, DY, ENS, FIX, HII, IESC, KTOS, MLI, MOD, NVT, NXT, QXO, RKLB, STRL, VICR, VMI, WTS
Information Technology: AMKR, CRDO, FORM, FN, FSLR, IONQ, LITE, LSCC, MDB, MKSI, NBIS, P, PATH, RIOT, RMBS, SANM, TTMI, ZETA, ZM
Materials: ALB, MP, RGLD
Utilities: TLN
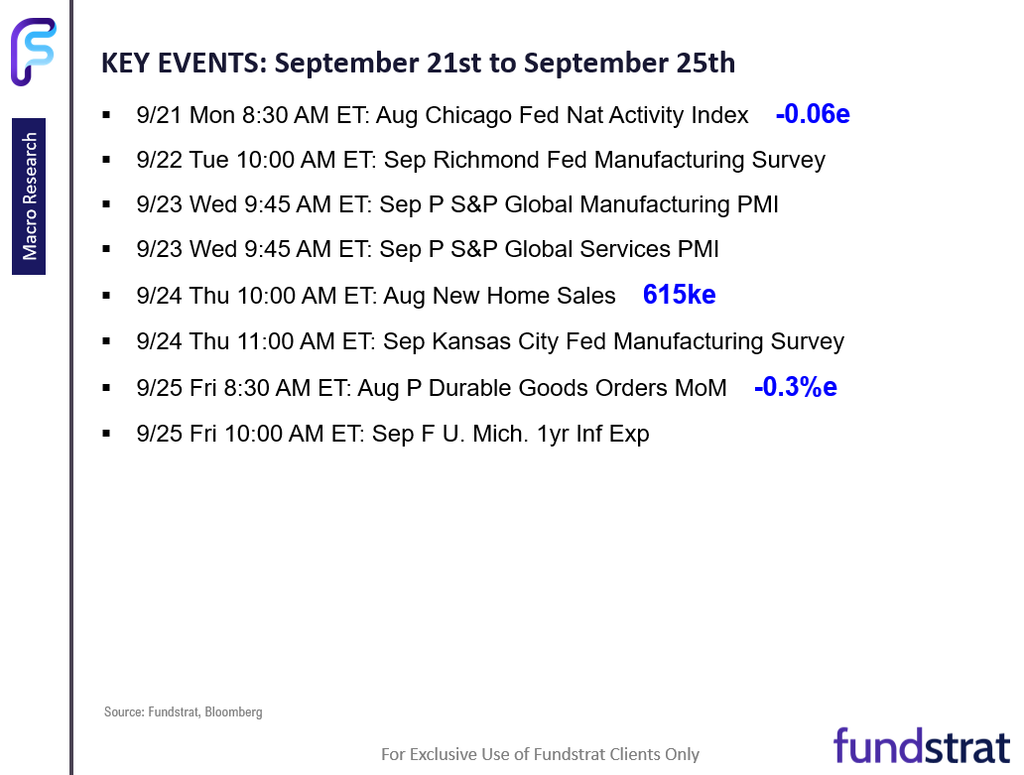
Key Incoming Data September:
9/1 9:45 AM ET: Aug F S&P Global Manufacturing PMITame9/1 10:00 AM ET: Jul JOLTS Job OpeningsTame9/1 10:00 AM ET: Aug ISM Manufacturing PMITame9/2 10:00 AM ET: Jul F Durable Goods OrdersTame9/3 8:30 AM ET: 2Q F Unit Labor CostsTame9/3 8:30 AM ET: 2Q F Non-Farm ProductivityTame9/3 8:30 AM ET: Jul Trade BalanceTame9/3 9:45 AM ET: Aug F S&P Global Services PMITame9/3 10:00 AM ET: Aug ISM Services PMITame9/4 8:30 AM ET: Aug Non-Farm PayrollsHot9/8 6:00 AM ET: Aug Small Business Optimism SurveyTame9/8 11:00 AM ET: Aug NY Fed 1yr Inf ExpTame9/10 8:30 AM ET: Aug PPITame9/10 10:00 AM ET: Aug Existing Home SalesTame9/11 8:30 AM ET: Aug CPITame9/11 10:00 AM ET: Sep P U. Mich. Sentiment and Inflation ExpectationMixed9/15 8:30 AM ET: Sep Empire Manufacturing SurveyTame9/16 8:30 AM ET: Aug Retail Sales DataTame9/16 10:00 AM ET: Sep NAHB Housing Market IndexTame9/16 2:00 PM ET: Sep FOMC DecisionHawkish9/16 4:00 PM ET: Jul Net TIC FlowsTame9/17 8:30 AM ET: Sep Philly Fed Business OutlookTame- 9/21 8:30 AM ET: Aug Chicago Fed Nat Activity Index
- 9/22 10:00 AM ET: Sep Richmond Fed Manufacturing Survey
- 9/23 9:45 AM ET: Sep P S&P Global Services PMI
- 9/23 9:45 AM ET: Sep P S&P Global Manufacturing PMI
- 9/24 10:00 AM ET: Aug New Home Sales
- 9/24 11:00 AM ET: Sep Kansas City Fed Manufacturing Survey
- 9/25 8:30 AM ET: Aug P Durable Goods Orders
- 9/25 10:00 AM ET: Sep F U. Mich. Sentiment and Inflation Expectation
- 9/28 10:30 AM ET: Sep Dallas Fed Manuf. Activity Survey
- 9/29 9:00 AM ET: Jul S&P Cotality CS 20-City MoM SA
- 9/29 10:00 AM ET: Aug JOLTS Job Openings
- 9/29 10:00 AM ET: Sep Conference Board Consumer Confidence
- 9/30 8:30 AM ET: 2Q T GDP
- 9/30 8:30 AM ET: Aug PCE Deflator
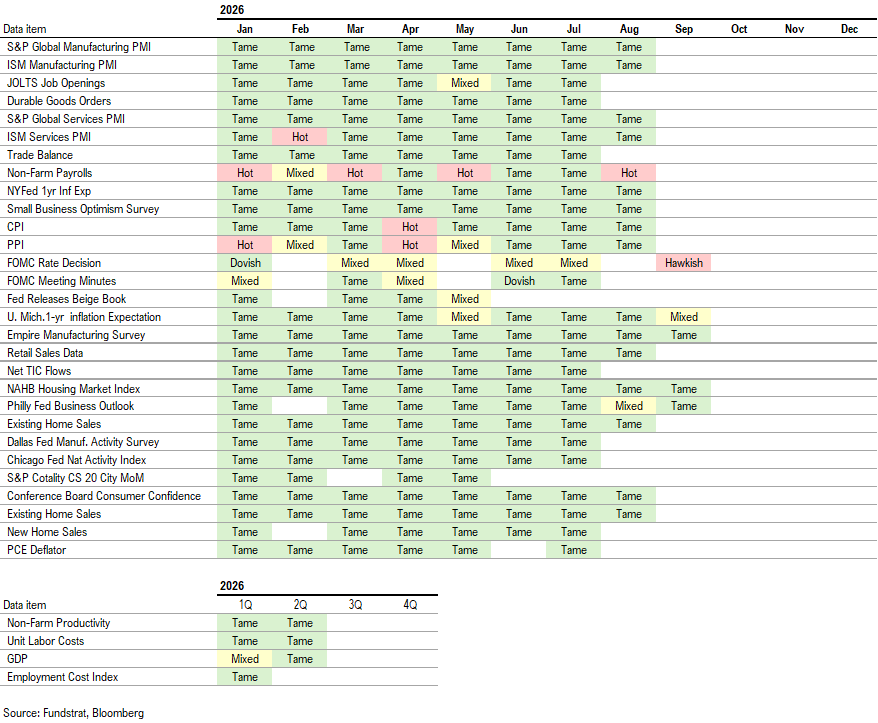
Economic Data Performance Tracker 2026:
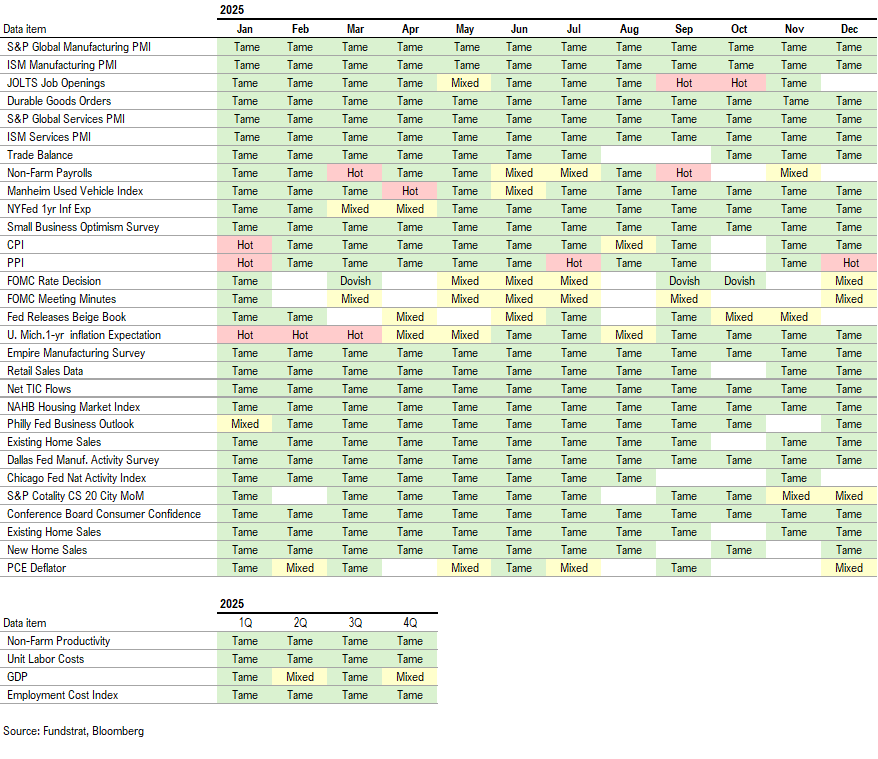
Economic Data Performance Tracker 2025:
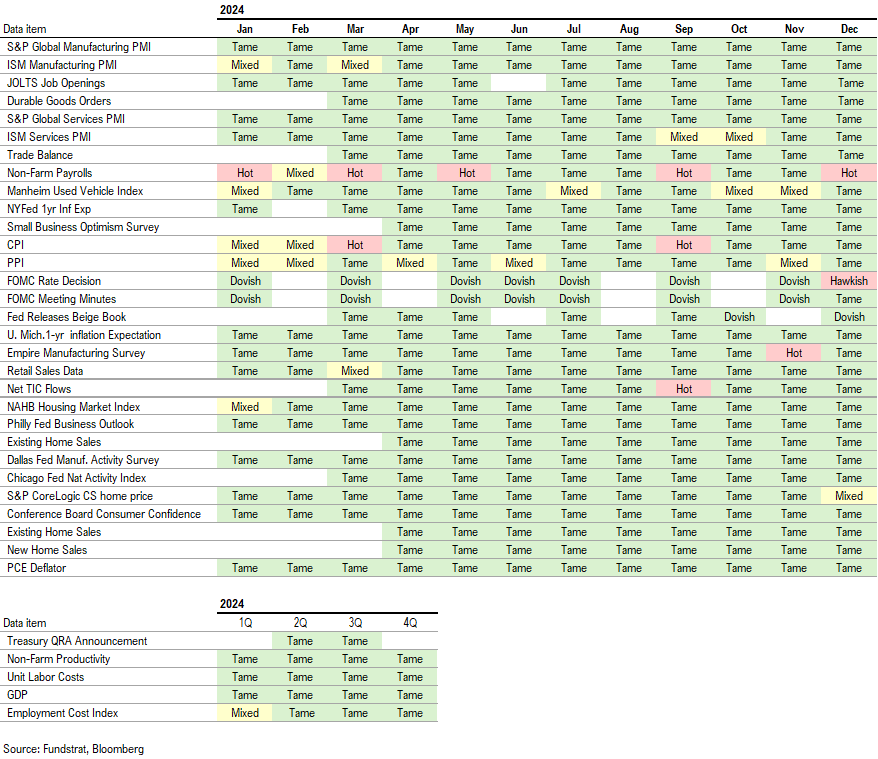
Economic Data Performance Tracker 2024:
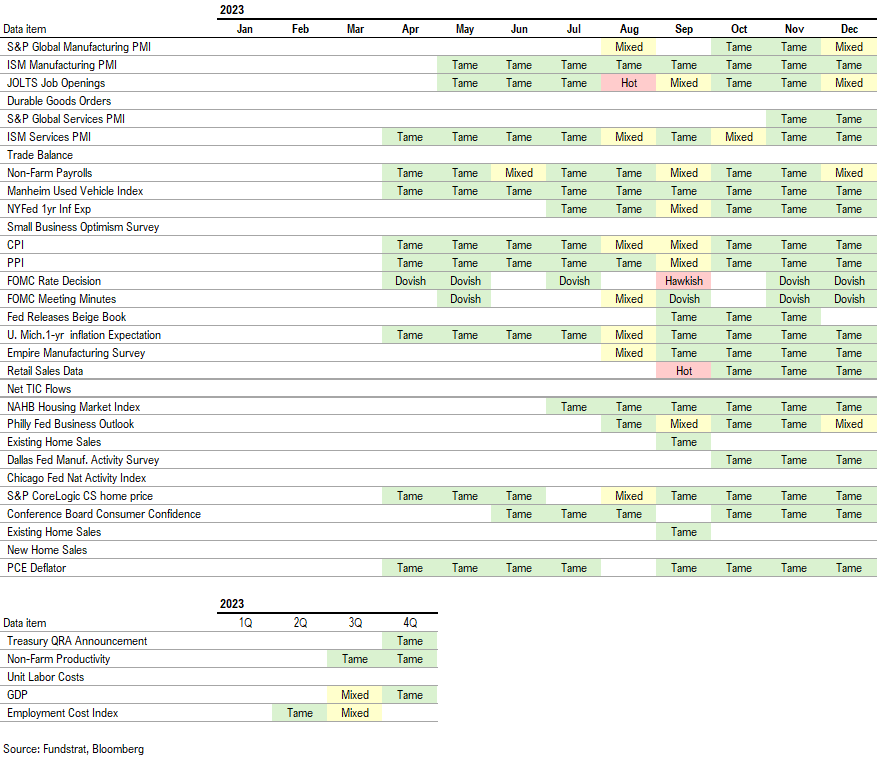
Economic Data Performance Tracker 2023:
______________________________
PS: If you are enjoying our service and its evidence-based approach, please leave us a positive 5-star review on Google reviews —> Click here.