

The S&P 500 limped into month end with a “whimper” finishing the month essentially flat (down -0.4%). This is not the worst outcome given that incoming news for the month was “bad” and “worse” than expected.
- September “negative” developments weighing in on markets:
– Fed Chair Warsh became a “full blown hawk” and raised rates +25bp
– August jobs report was surprisingly strong with 162,000 jobs added = hawkish
– US 10Y surged from 4.75% to 5.29%, +54bp
– US WTI oil hit $105 per barrel but for the month $85.76 to $88.89, +3.6%
– September is a seasonally bad month in a midterm year - In spite of these negative developments and headwinds, the S&P 500 managed a better than expected outcome of flat. To us, this is a somewhat disappointing outcome given that market sentiment had been so negative and that markets had reached an oversold status earlier in the month.
- But to us, the bigger takeaway might be that despite these substantial headwinds, particularly the surge in yields. Bond yields rose to nearly 20 year highs and these gains have been seen around the world. A US 10-year bond yielding 5.3% is becoming somewhat competitive as a total return prospect.
- Why are yields are rising? There are several possible explanations:
– fiscal deficits are creating credit risk
– AI spending and borrowing is competing for debt markets
– markets might see “long-term inflation” as higher
– term premium is rising, meaning uncertainty is adding to “yield” for longer years
– Fed might have signaled need to “crush” inflation sending cost of capital higher - Who knows? And this is why markets were unsettled for the month. But again, we view the flat performance of equities as evidence that underlying equity fundamentals have been strong. That is, the stock market should have been far stronger in the month, if bond yields did not surge in the month.
- There are some positives that have developed as we exit September and move into October:
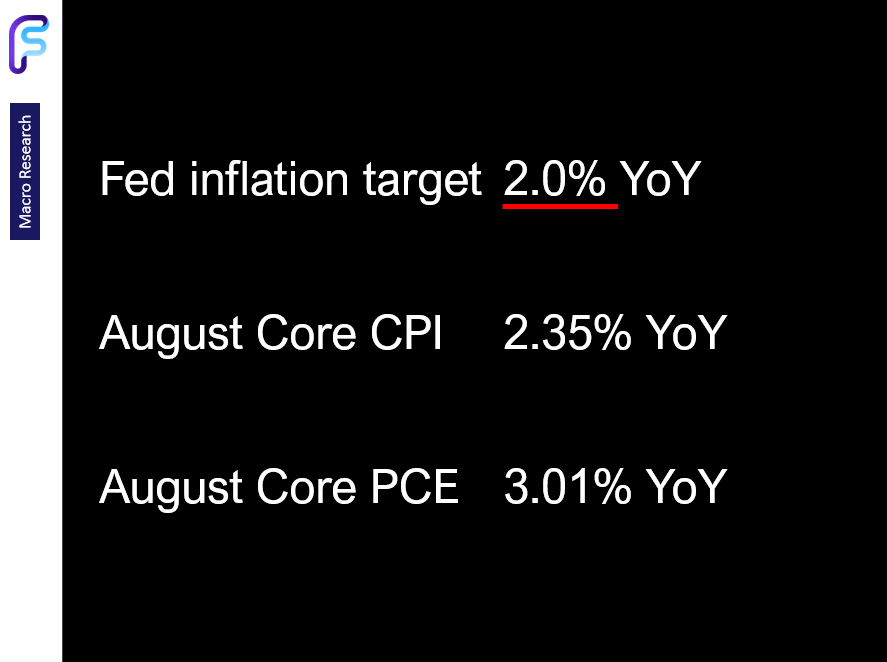
– the gap between Core PCE (3.0% now) vs Core CPI (2.35% now) is narrowing
– gap is now 65 bp versus 100bp last month
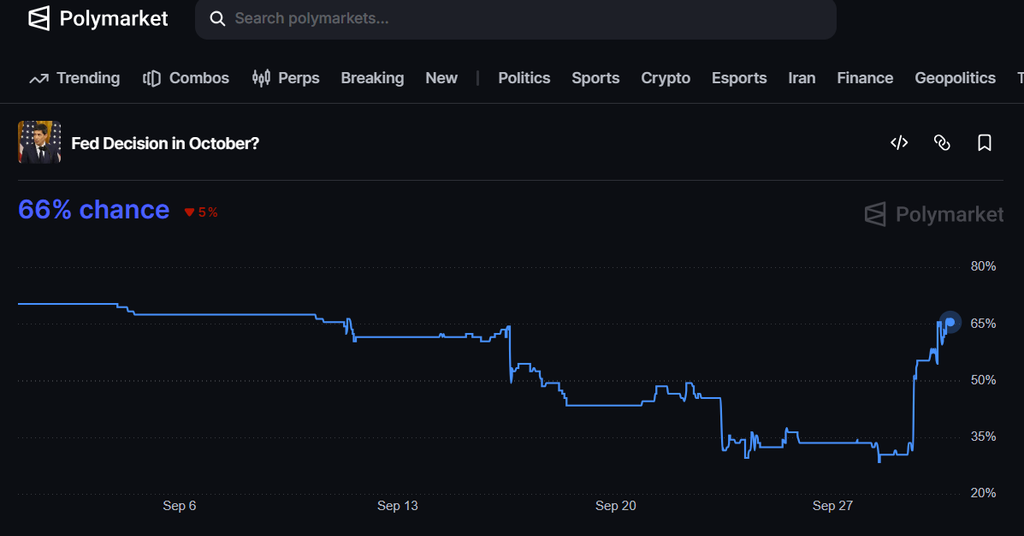
– odds of a Fed hike in Oct dropped to 36% from >75% after Fed’s Warsh “hawkish declaration”
– WTI oil has been downtrending for the past few weeks, after surging to $105
– US yields have risen for 7 months, and rarely in 75 years, manage to further rise beyond that - So, the setup for macro surprise in October might actually be more sanguine. Think about this:
– Fed fund futures show Fed likely to pause = dovish walkback
– Sept jobs report (Friday) could be soft = dovish walkback
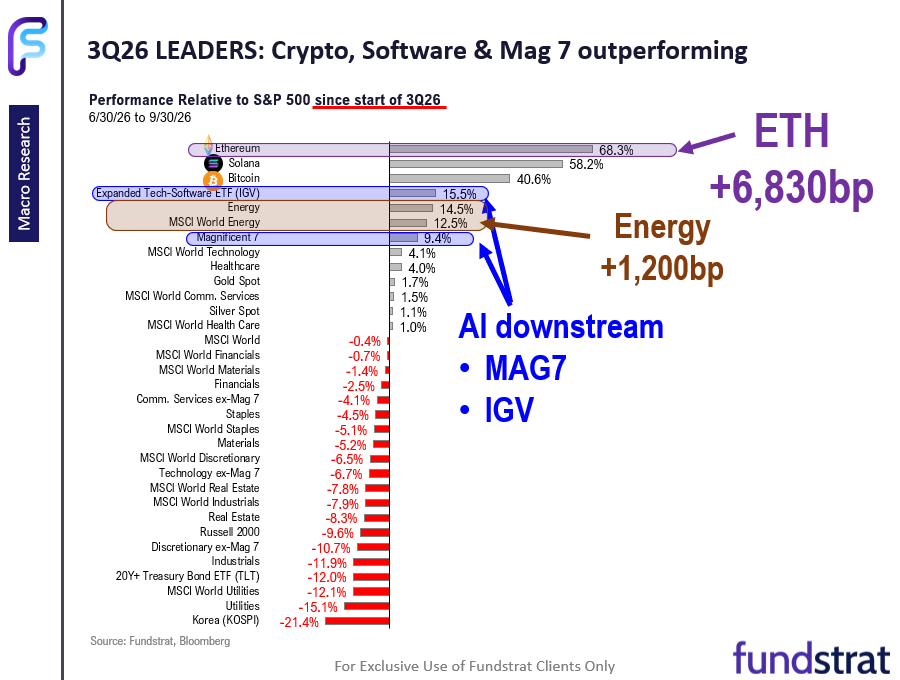
– Oil, if weaker, is disinflationary and could lower yields - This past 3Q26 was a challenging macro period for markets mainly because of the combination of factors mentioned above. That is, a hawkish pivot by the Fed and the surge in oil and yields. Moreover, the war continues to be the “long war.” In the face of this, here are the standout performers:
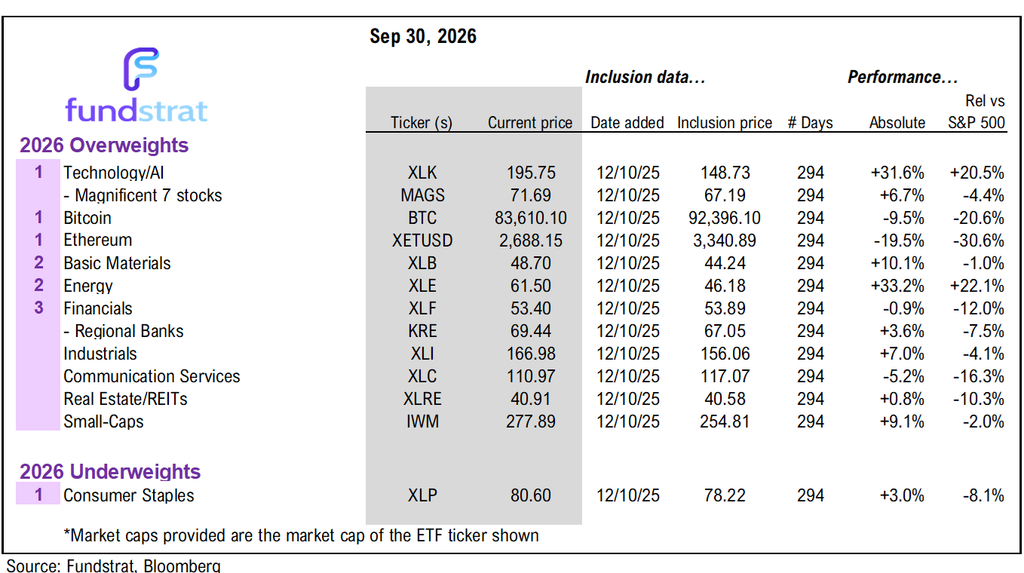
– Ethereum (ETH 0.35% ) and crypto with ETH leading by 6,830bp
– Software (IGV) outperforming by 1,550bp
– MAG7 (MAGS) outperforming by 940bp
– IGV and MAGS are “AI downstream” names and we had expected them to lead as AI corrected
– Energy given oil outperforming by 1,200bp - Of the above, Energy is not a surprise. But Crypto and MAGS and IGV showed considerable resilience in the face of a significant tightening of financial conditions (rates) and a hawkish Fed. To us, that is what we expect to lead in 4Q26 as well.
- In other words, we think the second half of 2026 will see leadership from:
– Ethereum and crypto –> full blown bull market underway
– MAGS and software IGV as AI downstream stories
– Energy is subject to how oil performs, which is an unknown - This week is a big week for macro data:
– 9/28 Mon 10:30 AM ET: Sep Dallas Fed Manuf. Activity Survey 10 vs 8e
– 9/29 Tue 9:00 AM ET: Jul S&P Cotality CS 20-City MoM SA 0.32% vs 0.20%
– 9/29 Tue 10:00 AM ET: Sep Conference Board Consumer Confidence 82 vs 89e
– 9/29 Tue 10:00 AM ET: Aug JOLTS Job Openings 7079k vs 7228ke
– 9/30 Wed 8:30 AM ET: Annual PCE & GDP Revision
– 9/30 Wed 8:30 AM ET: Aug Core PCE:
– Aug Core PCE MoM 0.25% vs 0.27%e
– Aug Core PCE YoY 3.01% vs 3.28%e
– 9/30 Wed 8:30 AM ET: 2Q T GDP QoQ 2.2% vs 1.5%e
– 10/1 Thu 9:45 AM ET: Sep F S&P Global Manufacturing PMI 57.0e
– 10/1 Thu 10:00 AM ET: Sep ISM Manufacturing PMI 54.9e
– 10/2 Fri 8:30 AM ET: Sep Non-farm Payrolls 90ke
– 10/2 Fri 10:00 AM ET: Aug F Durable Goods Orders MoM 0.0%e - In the coming week, there will be a lot of Fed speak, and this, in our view, will result in FOMC walking back on the “max hawkish” words of Warsh:
– 9/29 Tue 1:00 PM ET: Goolsbee Speaks in Moderated Discussion
– 9/29 Tue 2:00 PM ET: Williams Gives Keynote Remarks (voting)
– 9/30 Wed 1:30 PM ET: Barkin Gives Welcome Remarks at Rural America Conference
– 9/30 Wed 3:25 PM ET: Cook Speaks at Investing in Rural America Conference (voting)
– 9/30 Wed 5:10 PM ET: Goolsbee Gives Keynote Address
– 9/30 Wed 6:00 PM ET: Kashkari Speaks in Fireside Chat (voting)
– 10/1 Thu 9:05 AM ET: Barkin, Collins, Schmid on Panel About Rural America
– 10/1 Thu 3:30 PM ET: Cook and NY Fed’s Williams at Panel (voting)
– 10/1 Thu 6:45 PM ET: Logan Speaks At Eleventh District Appreciation Event (voting)
Bottom line: We expect stocks to rally into month-end
We realize investors feel worn down by the churning in the month of September. There were multiple negative macro developments in the past month. The headwinds are expected to be less severe in October. And as Tom Luddy and Susan Bao, both of JPMorgan, have told me many times, over the years, “less bad is good.” That may be the setup for October.
- Foremost, we believe underlying fundamentals remain solid
- Investor sentiment remains cautious and this adds asymmetry to risk/reward
- Equities saw a waterfall decline in the past week. In mid-August, such a waterfall decline was followed by a rally
- Incremental data, in our view, will be dovish, which will fuel further upside
The strength in crypto remains notable. Ethereum ETH 0.35% remains the best performing major macro asset in 3Q26. This bodes well for crypto to outperform in 4Q26.
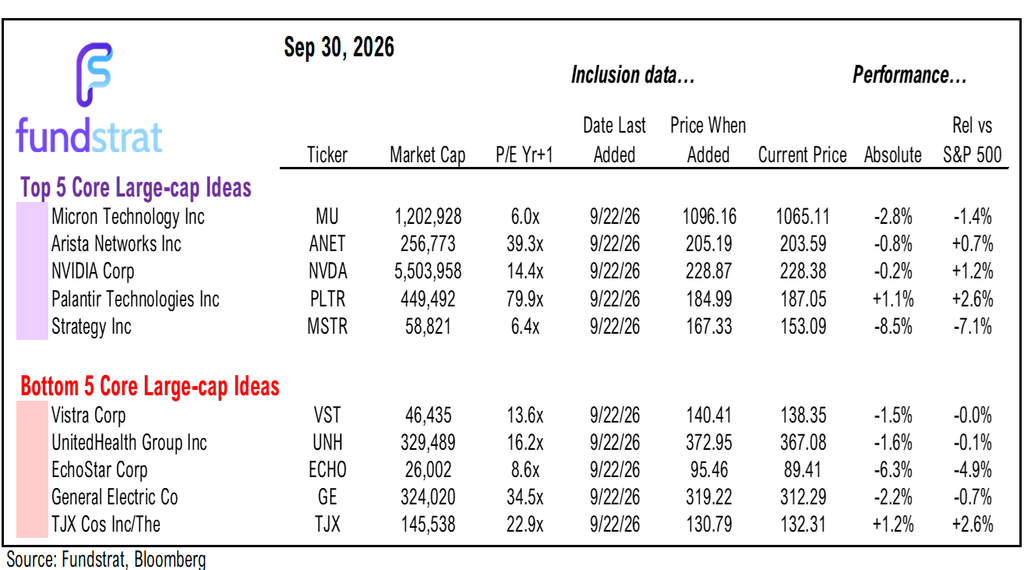
Part I: 46 Large-cap Core Ideas: Updated list is below
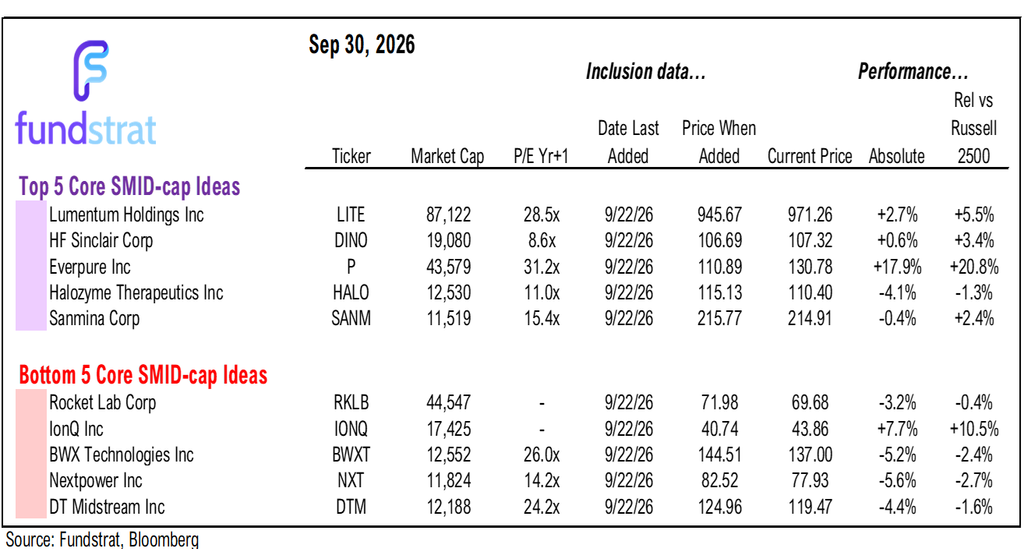
Large-Cap Core Stock Ideas are large-cap stocks that appear in multiple of our investment strategies.
- Consider these stocks our top stock picks and thus, the higher quality ideas.
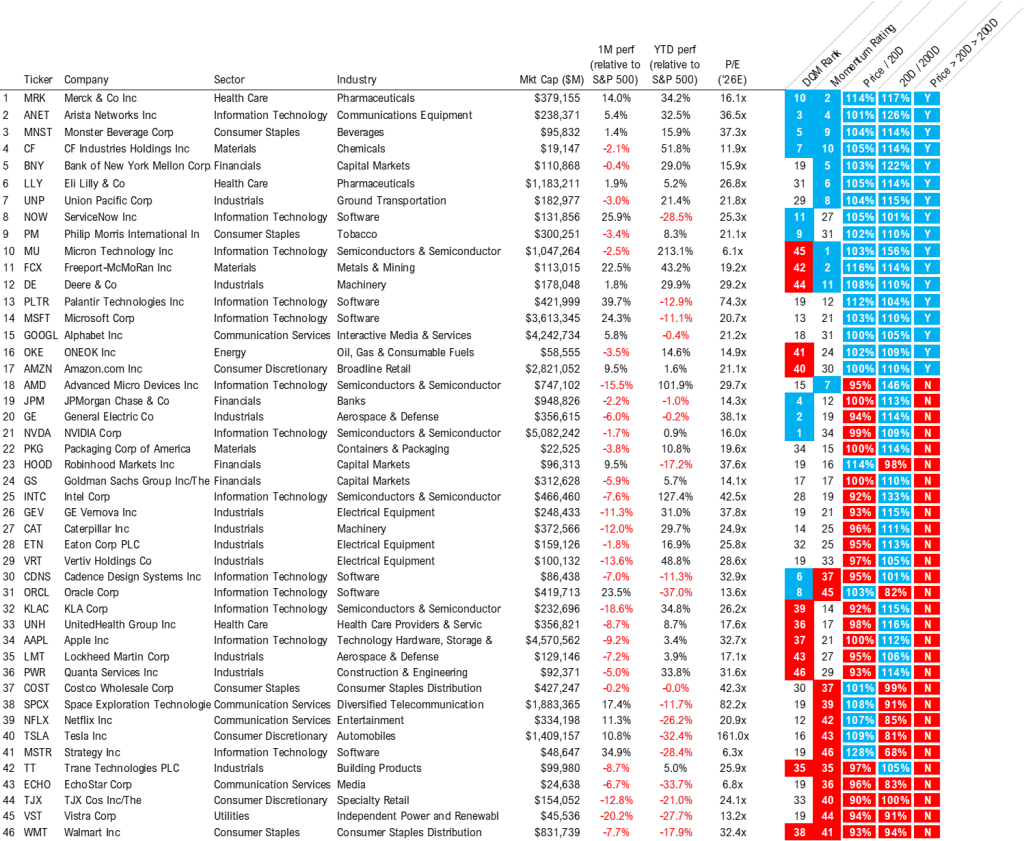
The Current Large-cap Core List as of 8/21/2026 is as follows:
Communication Services: ECHO, GOOGL, NFLX
Consumer Discretionary: AMZN, TJX, TSLA
Consumer Staples: COST, MNST, PM, WMT
Energy: OKE
Financials: BNY, GS, HOOD, JPM
Health Care: LLY, MRK, UNH
Industrials: CAT, DE, ETN, GE, GEV, LMT, PWR, SPCX, TT, UNP, VRT
Information Technology: AAPL, AMD, ANET, CDNS, INTC, KLAC, MSFT, MSTR, MU, NOW, NVDA, ORCL, PLTR
Materials: CF, FCX, PKG
Utilities: VST
Part II: 65 SMID Core Ideas: Updated list is below
SMID Core Ideas are small and mid-cap stocks that appear in multiple of our investment strategies.
- We believe SMID Core List could benefit from the multiple themes and secular tailwinds.
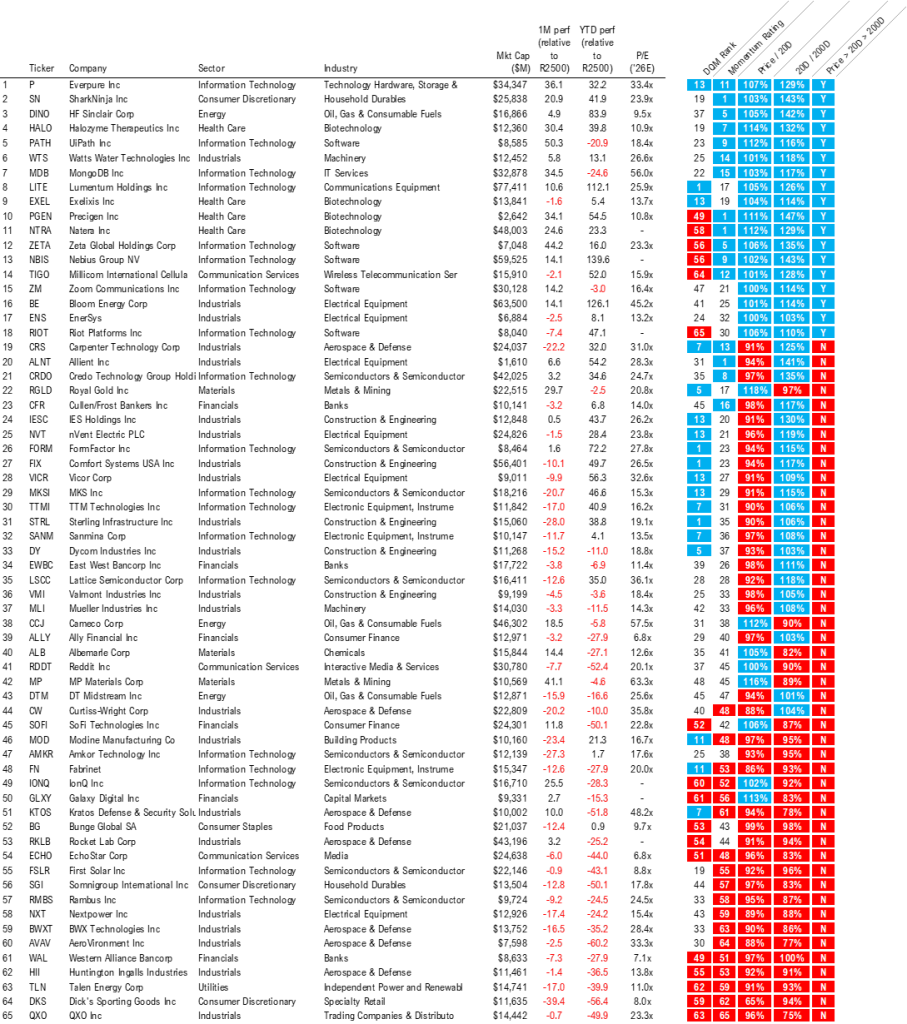
The Current SMID Core List as of 8/21/2026 is as follows:
Communication Services: ECHO, RDDT, TIGO
Consumer Discretionary: DKS, SGI, SN
Consumer Staples: BG
Energy: CCJ, DINO, DTM
Financials: ALLY, CFR, EWBC, GLXY, SOFI, WAL
Health Care: EXEL, HALO, NTRA, PGEN
Industrials: ALNT, AVAV, BE, BWXT, CRS, CW, DY, ENS, FIX, HII, IESC, KTOS, MLI, MOD, NVT, NXT, QXO, RKLB, STRL, VICR, VMI, WTS
Information Technology: AMKR, CRDO, FORM, FN, FSLR, IONQ, LITE, LSCC, MDB, MKSI, NBIS, P, PATH, RIOT, RMBS, SANM, TTMI, ZETA, ZM
Materials: ALB, MP, RGLD
Utilities: TLN
Key Incoming Data September:
9/1 9:45 AM ET: Aug F S&P Global Manufacturing PMITame9/1 10:00 AM ET: Jul JOLTS Job OpeningsTame9/1 10:00 AM ET: Aug ISM Manufacturing PMITame9/2 10:00 AM ET: Jul F Durable Goods OrdersTame9/3 8:30 AM ET: 2Q F Unit Labor CostsTame9/3 8:30 AM ET: 2Q F Non-Farm ProductivityTame9/3 8:30 AM ET: Jul Trade BalanceTame9/3 9:45 AM ET: Aug F S&P Global Services PMITame9/3 10:00 AM ET: Aug ISM Services PMITame9/4 8:30 AM ET: Aug Non-Farm PayrollsHot9/8 6:00 AM ET: Aug Small Business Optimism SurveyTame9/8 11:00 AM ET: Aug NY Fed 1yr Inf ExpTame9/10 8:30 AM ET: Aug PPITame9/10 10:00 AM ET: Aug Existing Home SalesTame9/11 8:30 AM ET: Aug CPITame9/11 10:00 AM ET: Sep P U. Mich. Sentiment and Inflation ExpectationMixed9/15 8:30 AM ET: Sep Empire Manufacturing SurveyTame9/16 8:30 AM ET: Aug Retail Sales DataTame9/16 10:00 AM ET: Sep NAHB Housing Market IndexTame9/16 2:00 PM ET: Sep FOMC DecisionHawkish9/16 4:00 PM ET: Jul Net TIC FlowsTame9/17 8:30 AM ET: Sep Philly Fed Business OutlookTame9/21 8:30 AM ET: Aug Chicago Fed Nat Activity IndexTame9/22 10:00 AM ET: Sep Richmond Fed Manufacturing SurveyTame9/23 9:45 AM ET: Sep P S&P Global Services PMIHot9/23 9:45 AM ET: Sep P S&P Global Manufacturing PMIHot9/24 10:00 AM ET: Aug New Home SalesTame9/24 11:00 AM ET: Sep Kansas City Fed Manufacturing SurveyTame9/25 8:30 AM ET: Aug P Durable Goods OrdersTame9/25 10:00 AM ET: Sep F U. Mich. Sentiment and Inflation ExpectationTame9/28 10:30 AM ET: Sep Dallas Fed Manuf. Activity SurveyTame9/29 9:00 AM ET: Jul S&P Cotality CS 20-City MoM SATame9/29 10:00 AM ET: Aug JOLTS Job OpeningsTame9/29 10:00 AM ET: Sep Conference Board Consumer ConfidenceTame9/30 8:30 AM ET: 2Q T GDPTame9/30 8:30 AM ET: Aug PCE DeflatorTame
Key Incoming Data October:
- 10/1 9:45 AM ET: Sep F S&P Global Manufacturing PMI
- 10/1 10:00 AM ET: Sep ISM Manufacturing PMI
- 10/2 8:30 AM ET: Sep Non-Farm Payrolls
- 10/2 10:00 AM ET: Aug F Durable Goods Orders
- 10/5 9:45 AM ET: Sep F S&P Global Services PMI
- 10/5 10:00 AM ET: Sep ISM Services PMI
- 10/6 8:30 AM ET: Aug Trade Balance
- 10/7 11:00 AM ET: Sep NY Fed 1yr Inf Exp
- 10/7 2:00 PM ET: Sep FOMC Meeting Minutes
- 10/9 10:00 AM ET: Oct P U. Mich. Sentiment and Inflation Expectation
- 10/13 6:00 AM ET: Sep Small Business Optimism Survey
- 10/13 10:00 AM ET: Sep Existing Home Sales
- 10/14 8:30 AM ET: Sep CPI
- 10/14 2:00 PM ET: Fed Releases Beige Book
- 10/15 8:30 AM ET: Sep PPI
- 10/15 8:30 AM ET: Oct Philly Fed Business Outlook
- 10/15 8:30 AM ET: Sep Retail Sales Data
- 10/16 4:00 PM ET: Aug Net TIC Flows
- 10/19 10:00 AM ET: Oct NAHB Housing Market Index
- 10/22 11:00 AM ET: Oct Kansas City Fed Manufacturing Survey
- 10/23 9:45 AM ET: Oct P S&P Global Services PMI
- 10/23 9:45 AM ET: Oct P S&P Global Manufacturing PMI
- 10/23 10:00 AM ET: Oct F U. Mich. Sentiment and Inflation Expectation
- 10/26 8:30 AM ET: Sep Chicago Fed Nat Activity Index
- 10/26 10:30 AM ET: Oct Dallas Fed Manuf. Activity Survey
- 10/27 8:30 AM ET: Sep P Durable Goods Orders
- 10/27 9:00 AM ET: Aug S&P Cotality CS 20-City MoM SA
- 10/27 10:00 AM ET: Sep New Home Sales
- 10/27 10:00 AM ET: Oct Richmond Fed Manufacturing Survey
- 10/27 10:00 AM ET: Oct Conference Board Consumer Confidence
- 10/28 2:00 PM ET: Oct FOMC Decision
- 10/29 8:30 AM ET: 3Q A GDP
- 10/29 8:30 AM ET: Sep PCE Deflator
- 10/30 8:30 AM ET: 3Q Employment Cost Index
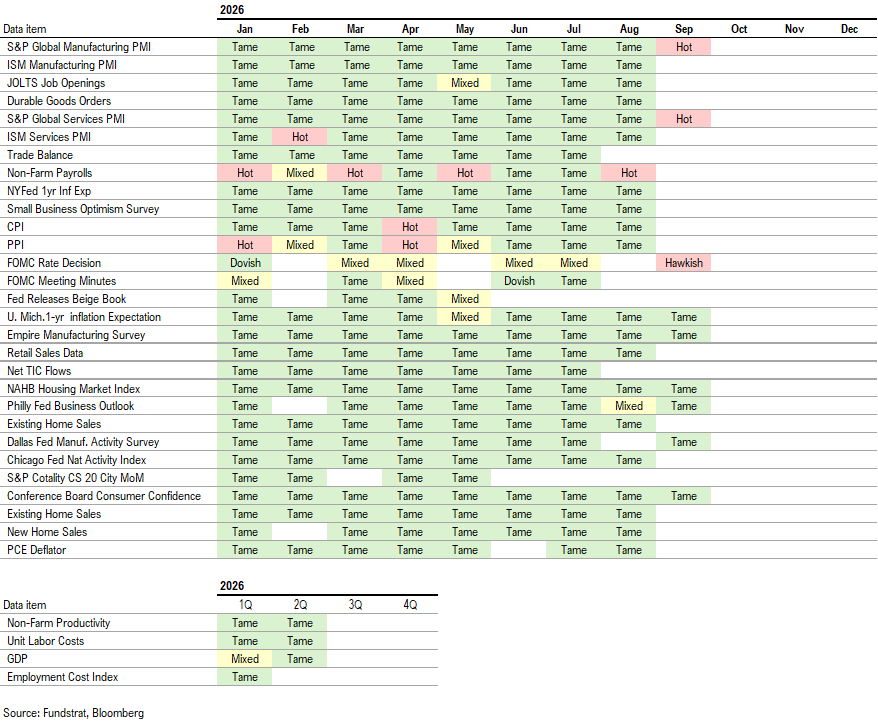
Economic Data Performance Tracker 2026:
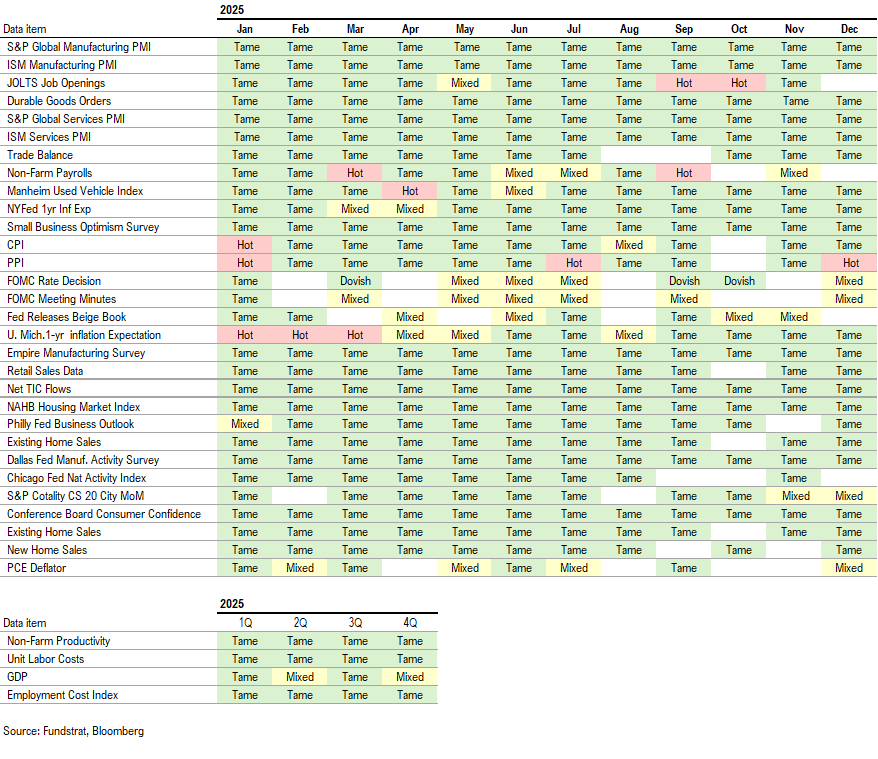
Economic Data Performance Tracker 2025:
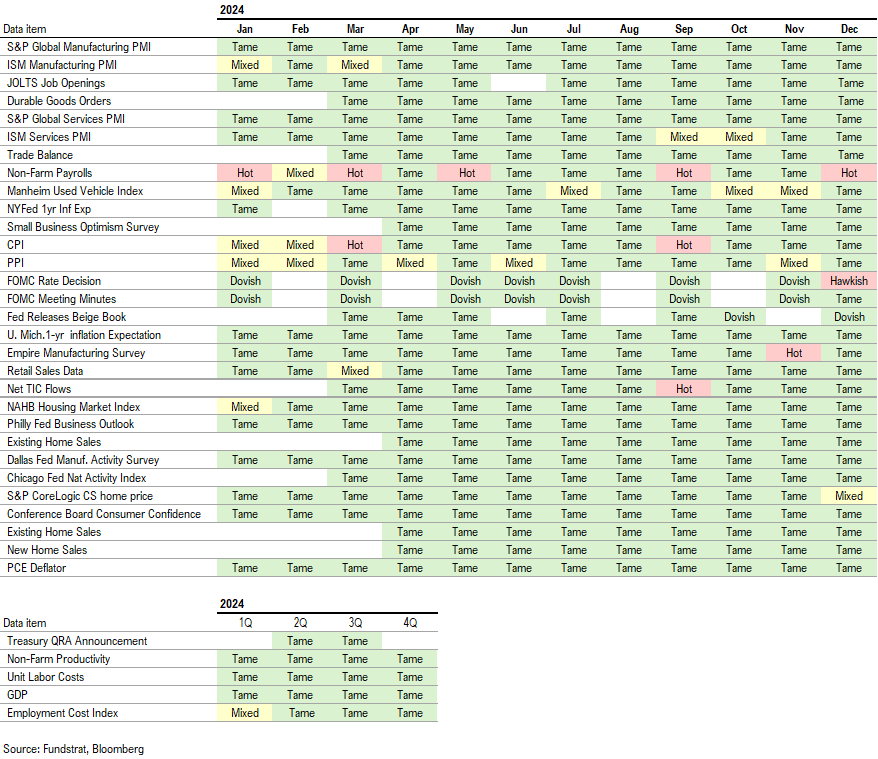
Economic Data Performance Tracker 2024:
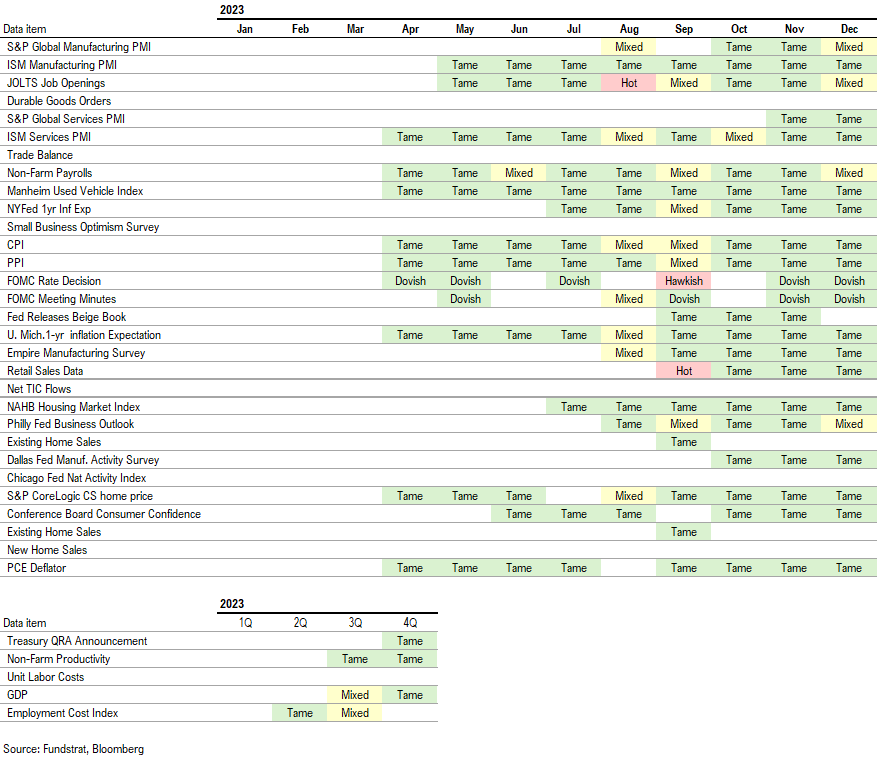
Economic Data Performance Tracker 2023:
______________________________
PS: If you are enjoying our service and its evidence-based approach, please leave us a positive 5-star review on Google reviews —> Click here.