

The S&P 500 registered a new high today (7,273 intraday high) and we continue to see positive risk/reward. While some investors remain wary and even skeptical of this strength in equities, in our view, the US stock market is rising for the right reasons.
- Foremost, the stocks leading this rally have been semiconductors, AI-exposed and technology stocks. These are all companies with strong near-term visibility and they produce things that are scarce, and thus, enable both good unit volume growth and margin expansion.
- In other words, these companies have strong fundamentals supporting the gains in equities. In fact, 1Q26 EPS that are rising are producing something scarce. To us, the following are visibly scarce:
– AI compute components, NVDA to memory MU, SNDK, etc.
– AI power generation components GEV to CAT to many products in that supply chain
– Petroleum products jet fuel and diesel
– scale computing enterprises META, GOOGL, AMZN, etc.
– US has arguably a surplus of these relative to the rest of the World - So, it should not be a surprise that the leadership since the Iran war started and leaders since the ceasefire are these very stocks MAG7, etc. And we believe these valuations remain attractive at 20X for companies like NVDA. After all, NVDA still has a P/E multiple below that of consumer staples such as COST and WMT.
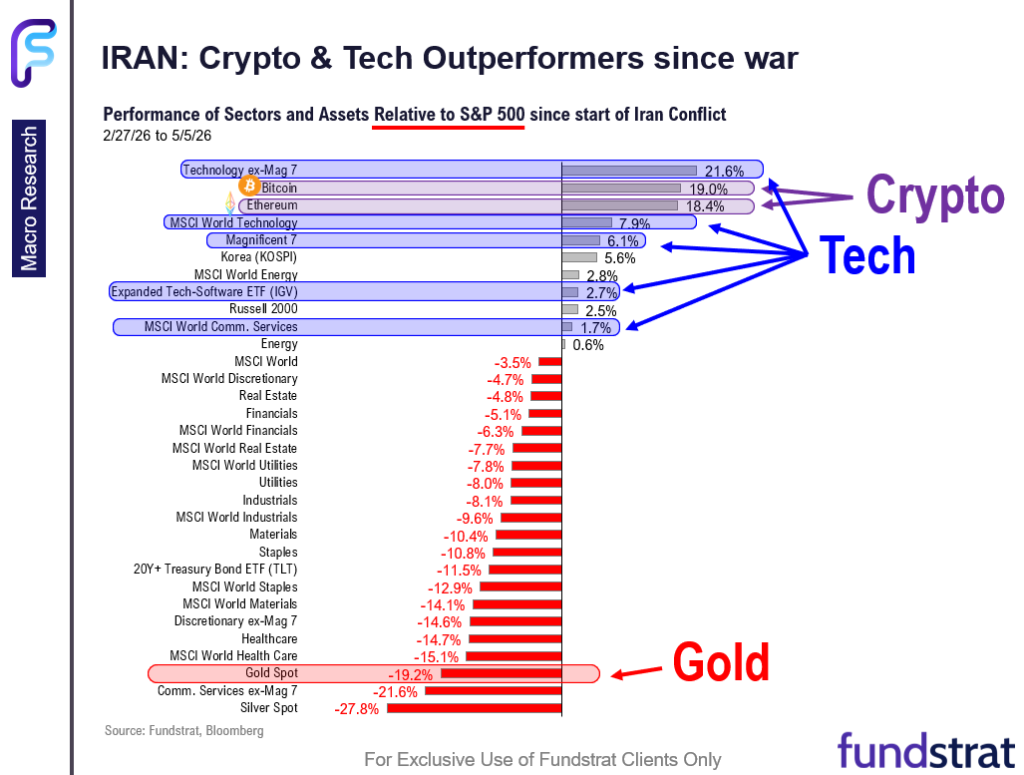
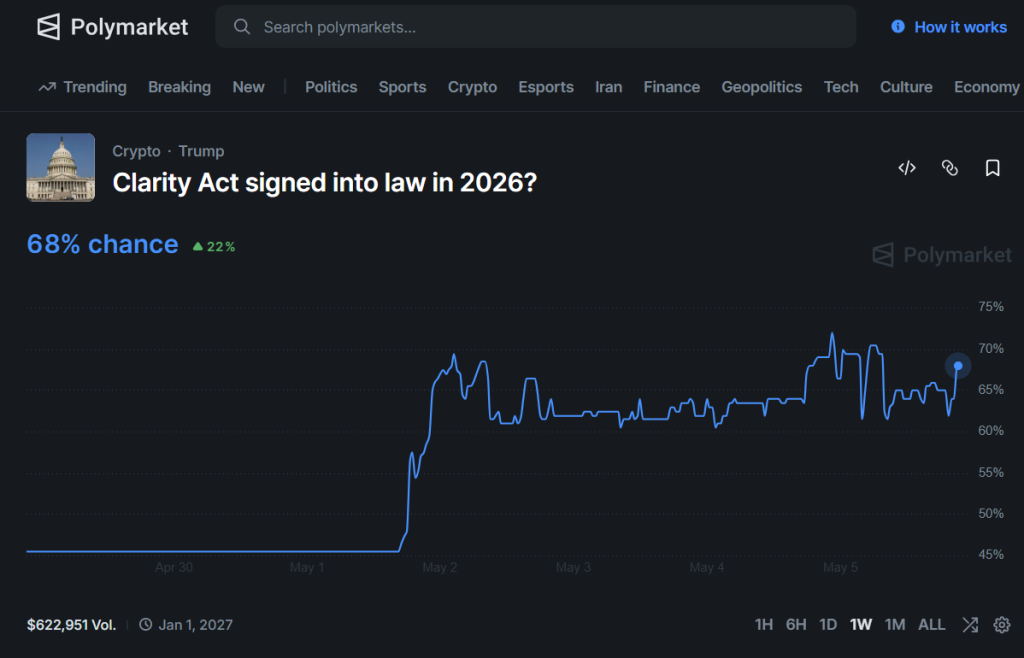
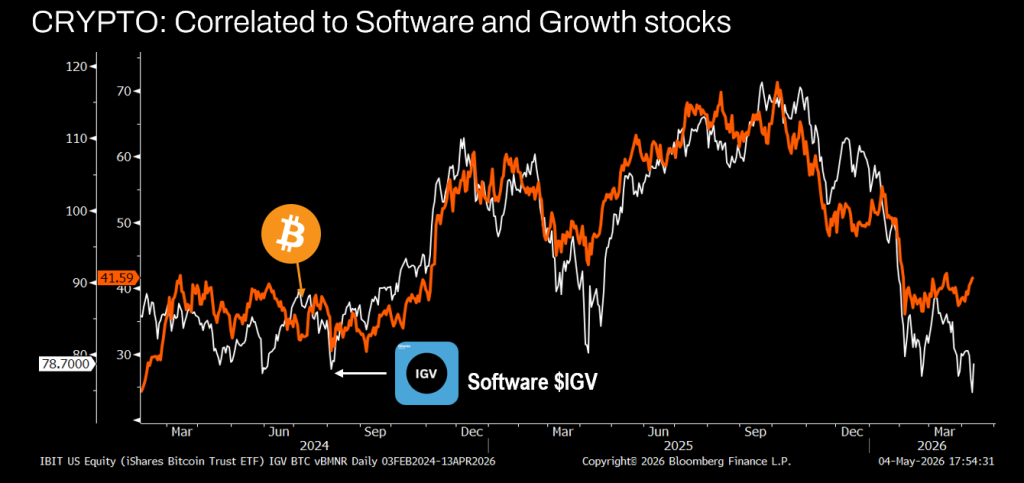
- Crypto has also lead since the Iran war started and in our view, digital assets reflect the synthesis of those exact same scarcities:
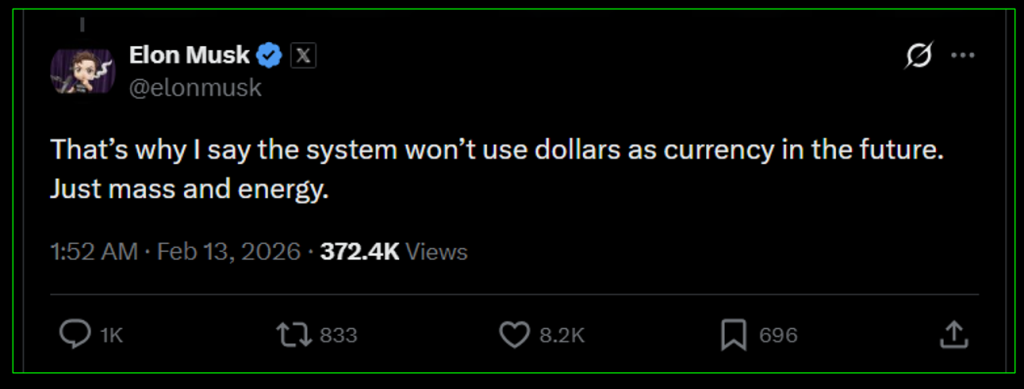
– Elon Musk in a recent X.com tweet stated:
“in future… the system won’t use dollars as currency in the future. Just mass and energy” - Mass and Energy refer to compute and to Energy. He has many times suggested this and noted that energy is the “basis for all industry.” So digital assets capture both compute and energy. The most obvious is Bitcoin BTC 1.53% . But this then has to be turned into units of currency that can be spent in the real world. This is where stablecoins and thus, Ethereum ETH 0.79% , play a role.
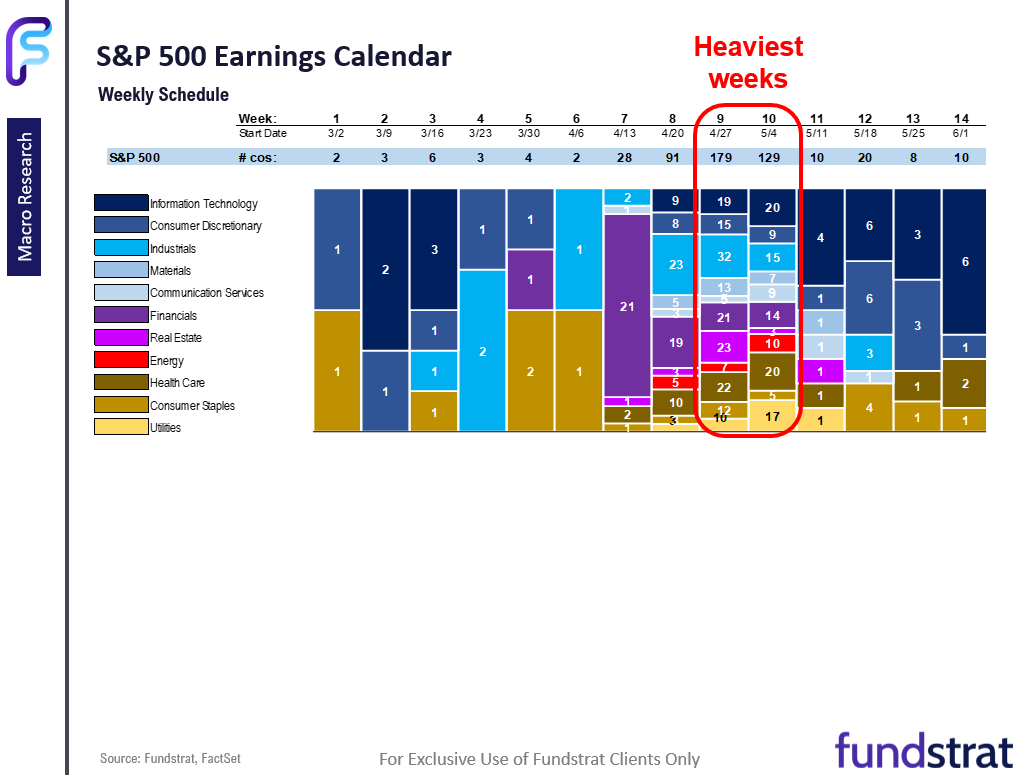
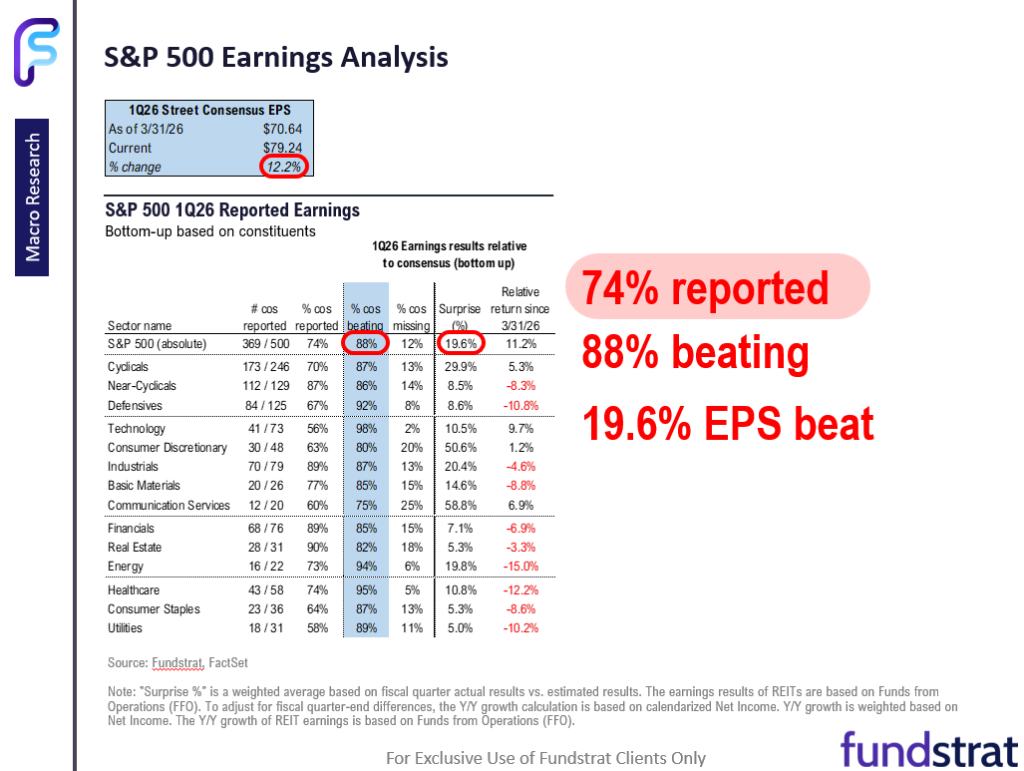
- We are also 74% through earnings season and a staggering 88% are beating estimates and the magnitude overall is 20%. This is the largest margin that we have seen in more than a decade.
– the beats are coming from Cyclicals (29% magnitude), not Defensives
– this is not a result of “lowered expectations” but rather, companies are seeing staggering demand - Any surprise stocks are doing well in earnings season?
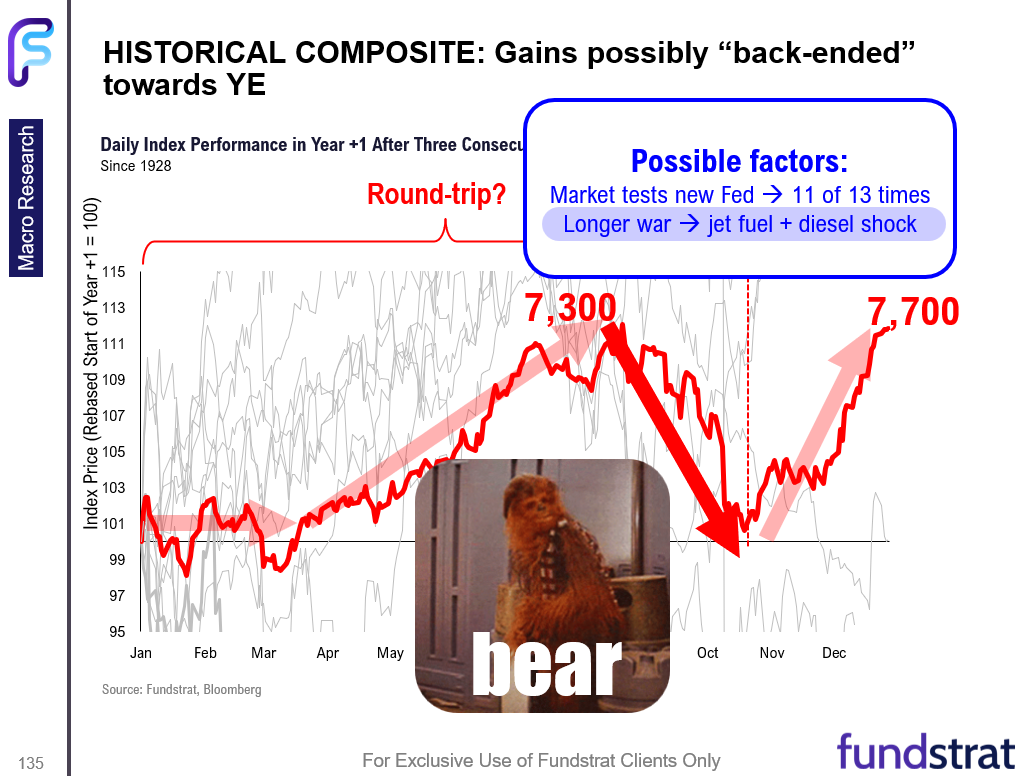
- Our base case remains a 3-phase market in 2026 and challenging overall:
– a rise to S&P 500 7,300
– then headwinds may emerge including market testing the Fed and energy shortages
– this leads to a drawdown of as much as 15% to 20%
– but then a year-end rally so strong, the S&P 500 rallies above 7,700. - This week key employment data is released, with the March JOLTS on Tuesday and the April Non-farm Payrolls on Friday:
– 5/4 Mon 10:00 AM ET: Mar F Durable Goods Orders MoM 0.8% vs 0.8%e
– 5/5 Tue 8:30 AM ET: Mar Trade Balance -60b vs -61be
– 5/5 Tue 9:45 AM ET: Apr F S&P Global Services PMI 51.0 vs 51.3e
– 5/5 Tue 10:00 AM ET: Apr ISM Services PMI 53.6 vs 53.7e
– 5/5 Tue 10:00 AM ET: Mar JOLTS Job Openings 6866k vs 6850ke
– 5/5 Tue 10:00 AM ET: Mar New Home Sales 682k vs 660ke
– 5/7 Thu 8:30 AM ET: 1Q P Nonfarm Productivity QoQ 1.0%e
– 5/7 Thu 8:30 AM ET: 1Q P Unit Labor Costs 2.5%e
– 5/7 Thu 11:00 AM ET: Apr NYFed 1yr Inf Exp 3.5%e
– 5/8 Fri 8:30 AM ET: Apr Non-farm Payrolls 65ke
– 5/8 Fri 10:00 AM ET: May P U. Mich. 1yr Inf Exp 4.8%e
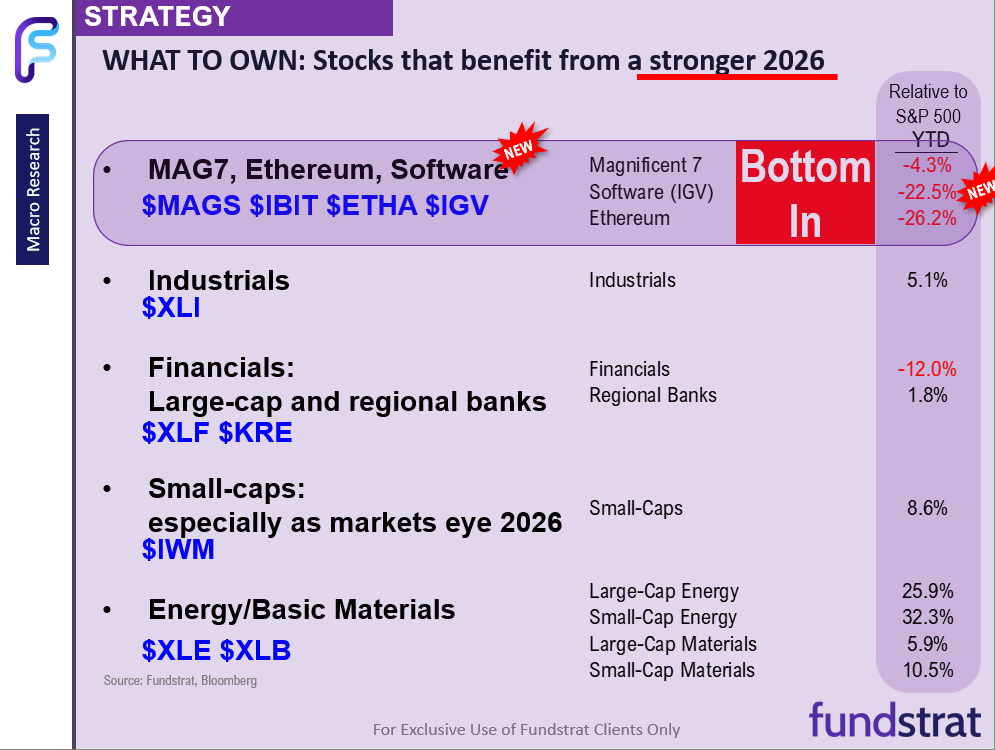
BOTTOM LINE: Crypto, MAG7, Software, Small-caps lead since Iran War
We believe the “war bottom” is in. We see a path towards S&P 500 7,300 prior to a larger potential pullback. But we also acknowledge that a larger pullback may not materialize. After all, we have seen sizable rolling bear markets in MAGS, crypto, Financials, Software. Thus, a lot of the market has experienced the needed de-rating.
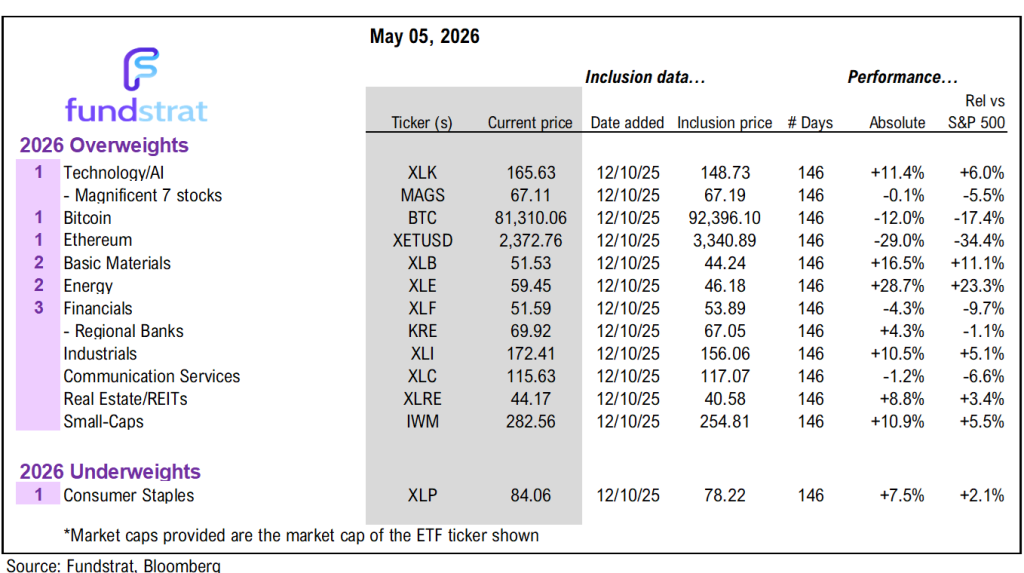
We continue to favor the following sectors:
- MAG7 & Bitcoin & Ethereum MAGS IBIT ETHA
- Industrials -> “bullet makers” XLI
- Financials: Large-cap and regional banks XLF KRE
- Small-caps IWM
- Energy/Basic Materials XLE XLB
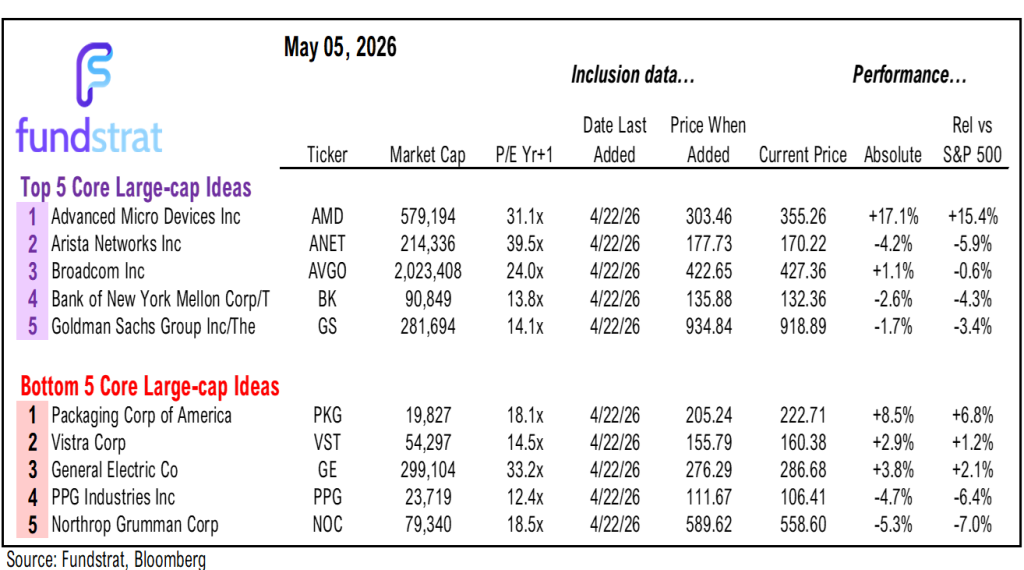
Part I: 44 Large-cap Core Ideas: Updated list is below
Large-Cap Core Stock Ideas are large-cap stocks that appear in multiple of our investment strategies.
- Consider these the stocks our top stock picks and thus, the higher quality ideas.
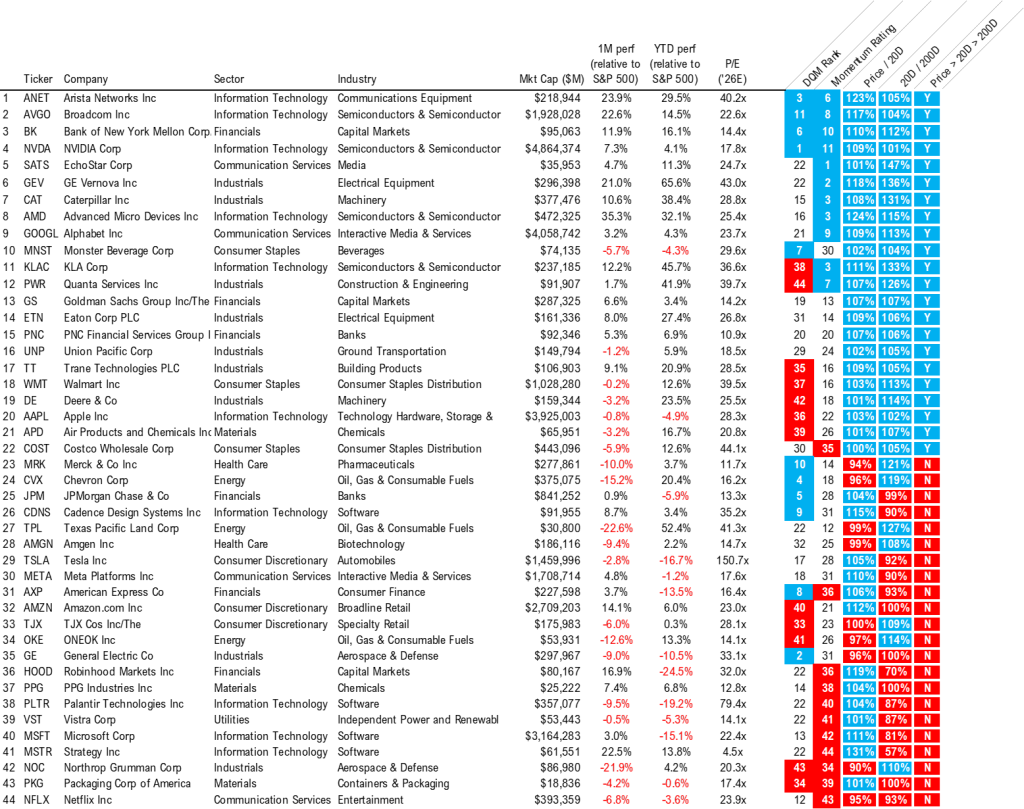
The Current Large-cap Core List as of 3/23/2026 is as follows:
Communication Services: GOOGL, META, NFLX, SATS
Consumer Discretionary: AMZN, TJX, TSLA
Consumer Staples: COST, MNST, WMT
Energy: CVX, OKE, TPL
Financials: AXP, BK, GS, HOOD, JPM, PNC
Health Care: AMGN, MRK
Industrials: CAT, DE, ETN, GE, GEV, NOC, PWR, TT, UNP
Information Technology: AAPL, AMD, ANET, AVGO, CDNS, KLAC, MSFT, MSTR, NVDA, PLTR
Materials: APD, PKG, PPG
Utilities: VST
Part II: 62 SMID Core Ideas: Updated list is below
SMID Core Ideas are small and mid-cap stocks that appear in multiple of our investment strategies.
- We believe SMID Core List could benefit from the multiple themes and secular tailwinds.
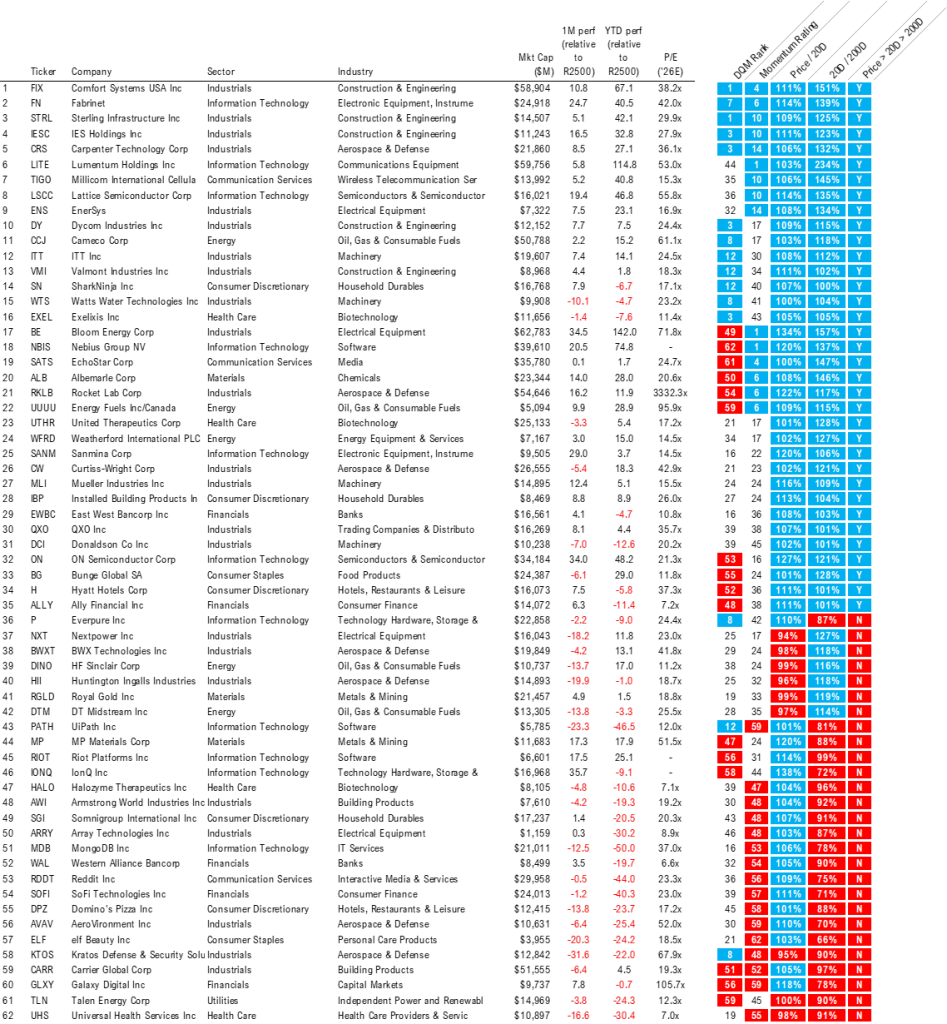
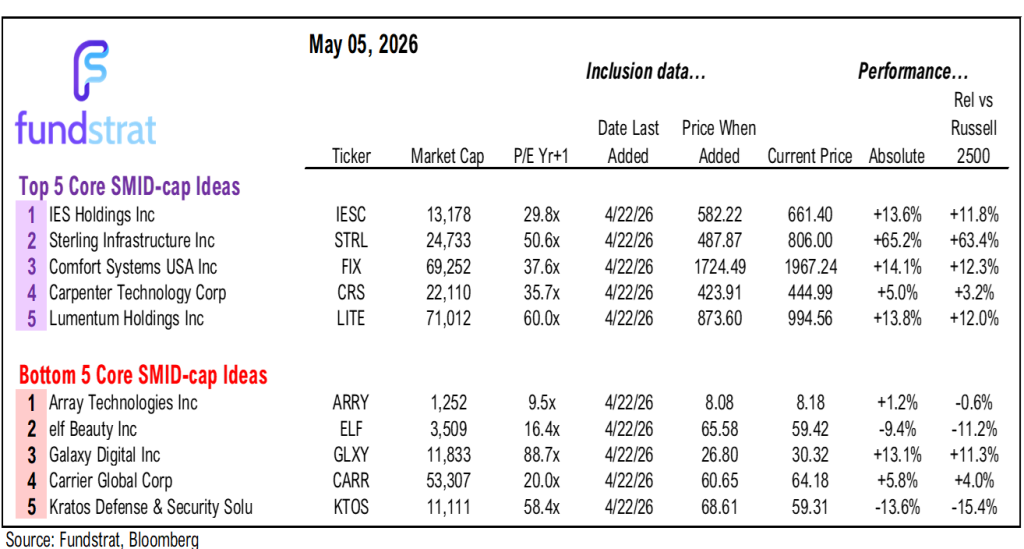
The Current SMID Core List as of 3/23/2026 is as follows:
Communication Services: RDDT, SATS, TIGO
Consumer Discretionary: DPZ, H, IBP, SGI, SN
Consumer Staples: BG, ELF
Energy: CCJ, DINO, DTM, UUUU, WFRD
Financials: ALLY, EWBC, GLXY, SOFI, WAL
Health Care: EXEL, HALO, UHS, UTHR
Industrials: ARRY, AVAV, AWI, BE, BWXT, CARR, CRS, CW, DCI, DY, ENS, FIX, HII, IESC, ITT, KTOS, MLI, NXT, QXO, RKLB, STRL, VMI, WTS
Information Technology: FN, IONQ, LSCC, LITE, MDB, NBIS, ON, P, PATH, RIOT, SANM
Materials: ALB, MP, RGLD
Utilities: TLN
Key Incoming Data May:
5/1 9:45 AM ET: Apr F S&P Global Manufacturing PMITame5/1 10:00 AM ET: Apr ISM Manufacturing PMITame5/4 10:00 AM ET: Mar F Durable Goods OrdersTame5/5 8:30 AM ET: Mar Trade BalanceTame5/5 9:45 AM ET: Apr F S&P Global Services PMITame5/5 10:00 AM ET: Mar JOLTS Job OpeningsTame5/5 10:00 AM ET: Mar New Home SalesTame5/5 10:00 AM ET: Apr ISM Services PMITame- 5/7 8:30 AM ET: 1Q P Unit Labor Costs
- 5/7 8:30 AM ET: 1Q P Non-Farm Productivity
- 5/7 11:00 AM ET: Apr NY Fed 1yr Inf Exp
- 5/8 8:30 AM ET: Apr Non-Farm Payrolls
- 5/8 10:00 AM ET: May P U. Mich. Sentiment and Inflation Expectation
- 5/11 10:00 AM ET: Apr Existing Home Sales
- 5/12 6:00 AM ET: Apr Small Business Optimism Survey
- 5/12 8:30 AM ET: Apr CPI
- 5/13 8:30 AM ET: Apr PPI
- 5/14 8:30 AM ET: Apr Retail Sales Data
- 5/15 8:30 AM ET: May Empire Manufacturing Survey
- 5/18 10:00 AM ET: May NAHB Housing Market Index
- 5/18 4:00 PM ET: Mar Net TIC Flows
- 5/20 2:00 PM ET: Apr FOMC Meeting Minutes
- 5/21 8:30 AM ET: May Philly Fed Business Outlook
- 5/21 9:45 AM ET: May P S&P Global Services PMI
- 5/21 9:45 AM ET: May P S&P Global Manufacturing PMI
- 5/21 11:00 AM ET: May Kansas City Fed Manufacturing Survey
- 5/22 10:00 AM ET: May F U. Mich. Sentiment and Inflation Expectation
- 5/25 8:30 AM ET: Apr Chicago Fed Nat Activity Index
- 5/26 9:00 AM ET: Mar S&P Cotality CS 20-City MoM SA
- 5/26 10:00 AM ET: May Conference Board Consumer Confidence
- 5/26 10:30 AM ET: May Dallas Fed Manuf. Activity Survey
- 5/27 10:00 AM ET: May Richmond Fed Manufacturing Survey
- 5/28 8:30 AM ET: 1Q S GDP
- 5/28 8:30 AM ET: Apr P Durable Goods Orders
- 5/28 8:30 AM ET: Apr PCE Deflator
- 5/28 10:00 AM ET: Apr New Home Sales
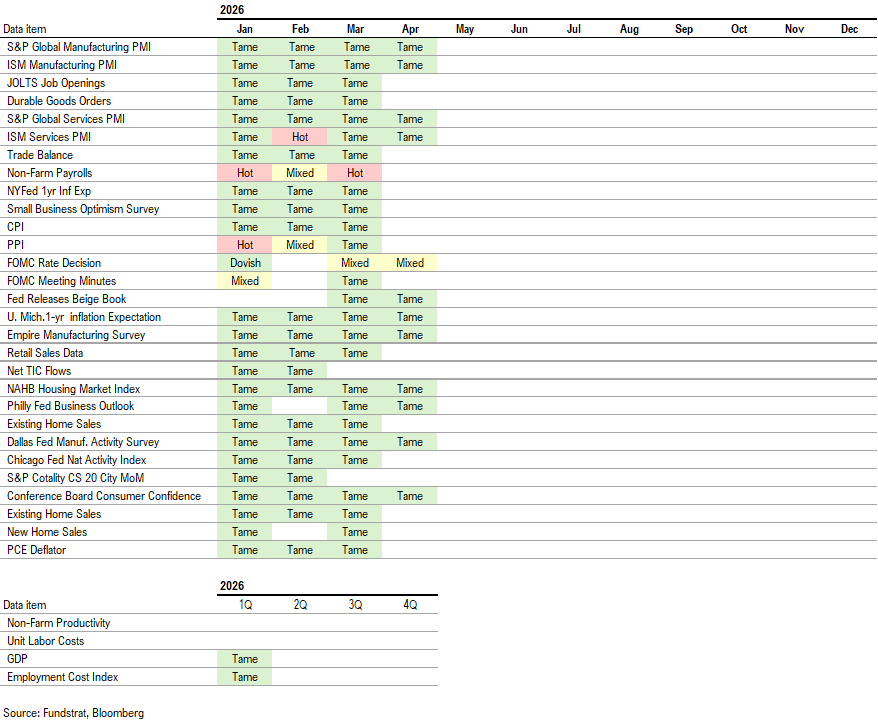
Economic Data Performance Tracker 2026:
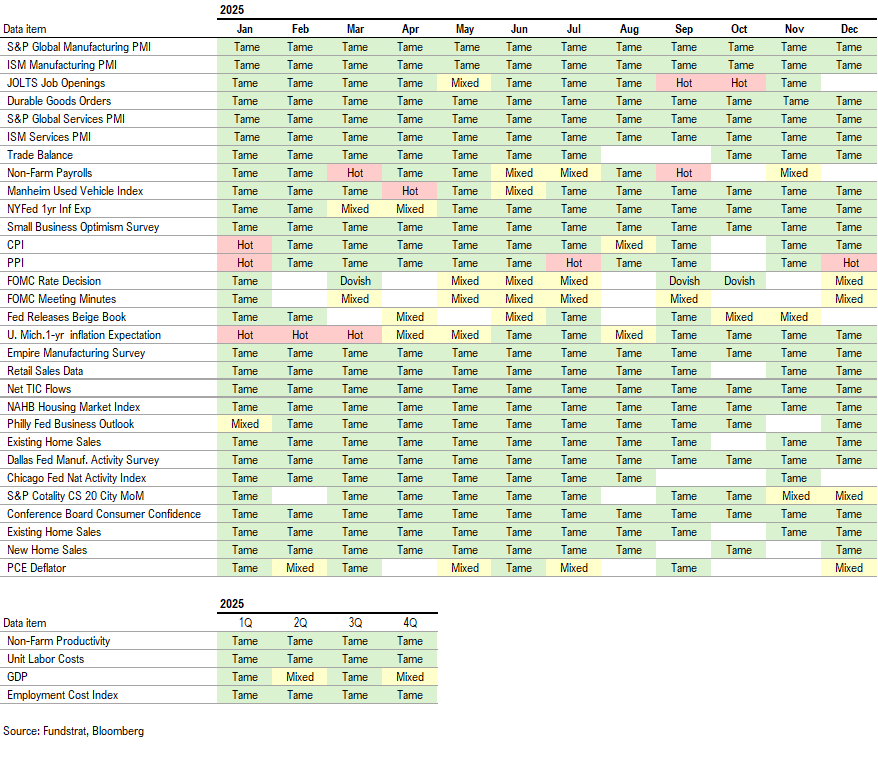
Economic Data Performance Tracker 2025:
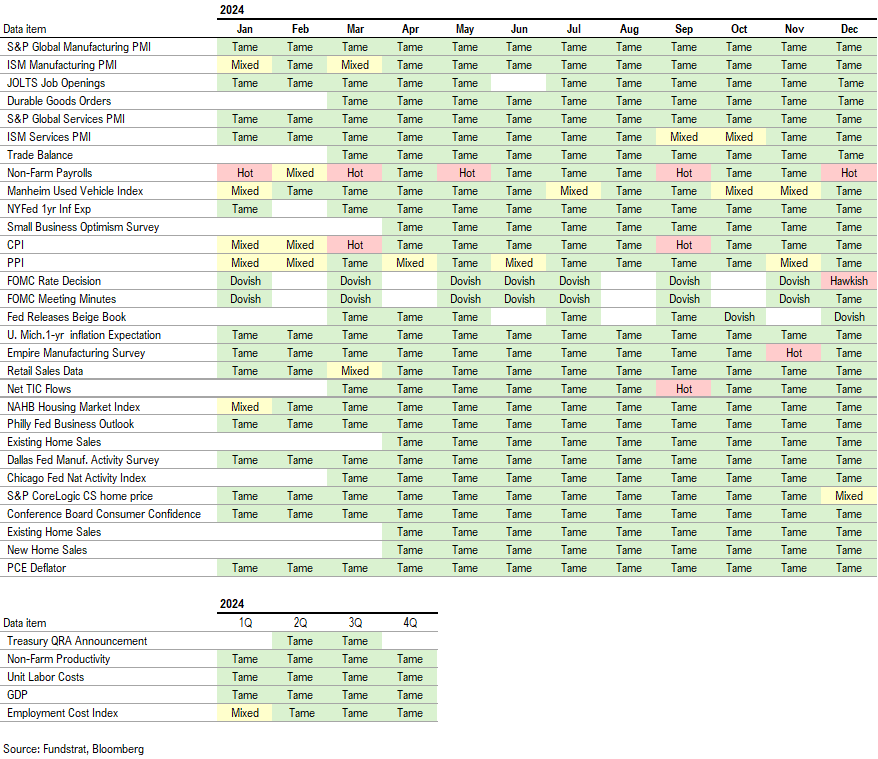
Economic Data Performance Tracker 2024:
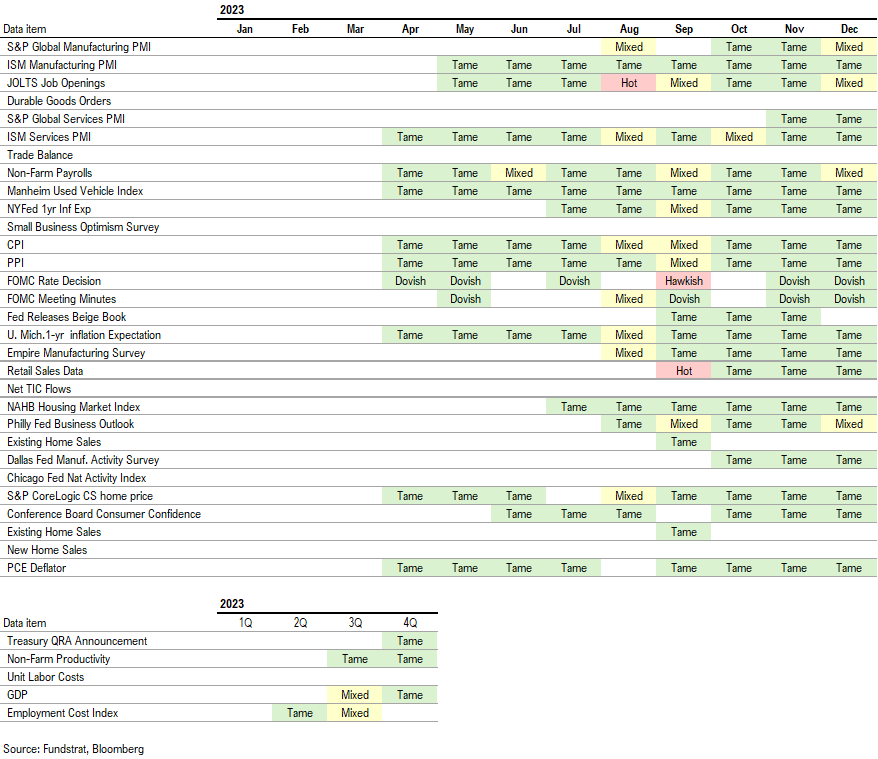
Economic Data Performance Tracker 2023:
______________________________
PS: If you are enjoying our service and its evidence-based approach, please leave us a positive 5-star review on Google reviews —> Click here.